From West African farms to a US courtroom, Lindt is learning that premium chocolate has a bitter aftertaste. But what does all this have to do with Roald Dahl?
Over the course of the last week, I’ve been steadily working my way through the Roald Dahl classic Charlie and the Chocolate Factory with my young daughter. Every day after school, she sits at the dining room table eating her lunch while I read to her about Golden Tickets, Oompa Loompas and Indian princes with melting chocolate palaces.
Dahl’s writing has been through some tough times in terms of having ideas and descriptions of characters that wouldn’t (and shouldn’t) make it past a modern editor. But beneath the problematic stuff, his writing is rich and descriptive. He brings a fantastical world to life with an ease that renders even my four-year-old content to sit still and listen (for a change).
But it was one particular passage, where he describes the bitterly poor protagonist Charlie Bucket’s strategy for making his annual birthday chocolate last, that transported me straight back to a moment from my own childhood:
“Then at last, when he could stand it no longer, he would peel back a tiny bit of the paper wrapping at one corner to expose a tiny bit of chocolate, and then he would take a tiny nibble – just enough to allow the lovely sweet taste to spread out slowly over his tongue. The next day he would take another tiny nibble, and so on, and so on. And in this way, Charlie would make his sixpenny bar of birthday chocolate last him for more than a month.”
There was only one chocolate bar that I treated with this level of reverence in my lifetime, and it was the first Lindt bar that I was given as a gift on my 11th birthday.
Why anyone thought that this was an appropriate gift for an 11-year-old I will never know – but from the moment I tore open the foil corner and caught a whiff of the rich chocolate inside, I knew that this was no ordinary KitKat or Bar-One. This was something special, to be eaten as slowly as possible.
Charlie managed to make his chocolate bar last for more than 30 days. I think mine lasted about 10, which is still impressive.
It’s easy to forget that even Willy Wonka’s fantastical chocolate factory had its dark days. Long before the Golden Tickets, he was forced to shut his gates and send his workers home.
Lindt hasn’t locked its doors, and there are no rival spies stealing recipes (as far as I know), but the Swiss chocolatier is facing a run of challenges that has seen it hike prices by 19% last year and almost 12% in the first half of this year. And then, earlier this week, the company sent its CEO packing.
These days, I suspect a lot more of us will be eating our Lindt the way Charlie ate his birthday bar: in tiny nibbles, making it last. Not out of reverence, but out of necessity.
A bittersweet supply chain
Lindt’s troubles begin nearly 5,000 km north of where I sit reading at my dining room table, on the cocoa farms of Ghana and Côte d’Ivoire.
Let me sketch the landscape as it stands today. West Africa produces about 70% of the world’s cocoa. That’s really close to having all your eggs in one basket, which means that any disruption in the region is almost guaranteed to have a global knock-on effect. In recent years, the region has been battered by erratic weather and crop disease.
Every chocolate maker has felt the squeeze, but many mass-market brands found a workaround. They shrank their bars, cut the cocoa and bulked up their recipes with cheaper vegetable fats, sometimes to the point where the result can only be sold as “chocolate-flavoured”.
Lindt’s problem is that they can’t take that shortcut without breaking the very promise that made me ration my birthday bar all those years ago. Their reputation rests on high cocoa content, so cocoa makes up a far bigger share of their costs than it does for brands that lean on palm oil. And because chocolate makers buy their cocoa months or even years in advance, those costs took time to reach the shelf.
Lindt passed the costs on gradually. Last year, shoppers started to push back. This year, they have had enough.
It’s not hard to see why. When the cost of living climbs and belts tighten, a slab of the fancy stuff is one of the first things to be put back on the shelf. Shoppers in Germany, Switzerland and Austria, arguably Lindt’s heartland, turned out to be far more price-sensitive than the company expected. Even the weather piled on, as a sweltering European summer dampened appetites for chocolate. The result was that Lindt’s sales volumes fell 7.5% in the first half of 2026, which forced them to be more price competitive and introduce smaller packs.
I wondered whether weight-loss drugs might also be dampening demand. In the US, at least, they don’t appear to be. Many in the industry feared that Ozempic and Mounjaro would kill our cravings for sweets, but Lindt’s own US datasuggests the opposite. In 2025, households using GLP-1 drugs increased their spending on premium chocolate far faster than everyone else, trading mindless snacking for smaller, more luxurious treats. The craving hasn’t gone. It’s just developed expensive taste.
Cocoa prices have eased since their 2024 peak, but chocolate-lovers shouldn’t rejoice just yet. The outlook remains shaky. Ghana’s cocoa regulator expects next season’s harvest to fall by at least 16%. It blames bad weather, disease, ageing trees and illegal gold mining.
Illegal gold mining? How does that fit in?
With gold prices soaring and cocoa paying little, struggling farmers are selling or leasing their land to miners, who dig it up and leave it poisoned with mercury. It’s a desperate, short-term fix with a long effect, since that land rarely recovers.
Next door, things hardly look better: Côte d’Ivoire, the world’s largest grower, is bracing for a drop of more than 10%.
The dark heart
While reading Charlie and the Chocolate Factory aloud, I am reminded of the fact that Mr Wonka’s spectacular factory is staffed exclusively by Oompa Loompas. These are described as small people, formerly jungle-dwelling, who Mr Wonka convinces to live and work in his factory in exchange for cocoa beans.
Therein lies one of the problematic elements of Dahl’s writing. This is the better version, as the original book in 1964 had the Oompa Loompas as black pygmies, shipped straight from Africa. He rewrote them as magical Oompa Loompas in 1973 after criticism from the NAACP (a civil rights organisation) and a very public spat with the children’s author Eleanor Cameron.
The pygmies may be gone, but the parallel with a terrible situation around real children picking cocoa in West Africa is hard to ignore.
Earlier this year, International Rights Advocates, a Washington DC-based law firm, sued Lindt. In July, the case moved to a US federal court. It alleges that Lindt has known for more than 20 years that children work on the Ghanaian and Ivorian farms that supply its cocoa, and that it has gone on profiting regardless.
Notably, the lawsuit isn’t after money. Its target is the wrapper. The firm argues that the ethical certifications printed on Lindt’s packaging lead shoppers to see the company as a force against child labour, while alleging that Lindt’s actual efforts have fallen short of those claims. In other words, it takes aim at what a premium brand sells alongside the chocolate: the sense that you’re buying something good, in every sense of the word.
Lindt denies the allegations and says it condemns all forms of child labour. It points out that the same firm has brought similar cases against Nestlé, Mars and other chocolate makers. It says it investigates suspected cases of child labour in its supply chain, and says its sourcing programme relies on Rainforest Alliance certification.
Whatever the court decides, the case points to a problem that runs through the entire industry, and it’s the same one driving farmers to sell their land to gold miners: despite the premiums put on the chocolate bars, the essential cocoa that goes into them still doesn’t pay enough to live on.
A certification sticker can’t change that.
In Dahl’s story, the workers were paid in cocoa beans. In the real one, many of the people who grow them are paid too little to keep their children out of the fields.
Making it last
Charlie’s story has a happy ending (spoiler alert), but Lindt’s is still being written. Cocoa remains at the mercy of the weather, the lawsuit will take time to play out, and a permanent new CEO isn’t expected until the second quarter of 2027.
None of that will be settled by the time we finish the book. This leaves me at the dining room table with a question of my own: if both the story and the chocolate come with a slightly bitter aftertaste, should I keep either of them away from my daughter?
I don’t think so. Shielding her from everything complicated isn’t the same as raising her well, and it would cost her some of the best parts of being small. So we’ll keep reading Mr. Dahl, and when we reach the bits that haven’t aged well, we’ll stop and talk about them. And one day, when she’s old enough (somewhere comfortably past 11), I’ll hand her a bar of the fancy stuff, teach her to peel back the foil one corner at a time, and tell her that somebody grew what’s inside, and that they deserve to be paid properly for it.
The idealist in me hopes that, by then, the children of cocoa-growing families are in classrooms, listening to someone read them a (suitably revised) story about a chocolate factory.
About the author: Dominique Olivier
Dominique Olivier uses her love of storytelling and ideation to help brands solve problems.
Her first book, Lessons from Loss, has been published by Penguin Random House.
She is a weekly columnist in Ghost Mail and collaborates with The Finance Ghost on Ghost Mail Weekender, a Sunday publication designed to help you be more interesting.
This is just a taste of what Ghost Mail subscribers get to enjoy every morning in their inboxes. Subscribe to Ghost Mail and join the community of investors.
CMH on Chinese cars (JSE: CMH)
Combined Motor Holdings released a trading statement and interim results just one day apart. The finance team must’ve worked very hard to achieve such clarity in the space of just 24 hours!
This poor financial reporting habit is at odds with the candid nature of the results commentary. I wish more companies wrote their management narrative the way that CMH does. I also wish that more companies would put some daylight between the trading statement and the release of results.
Anyway, the company put in a strong performance for the six months to August 2026.
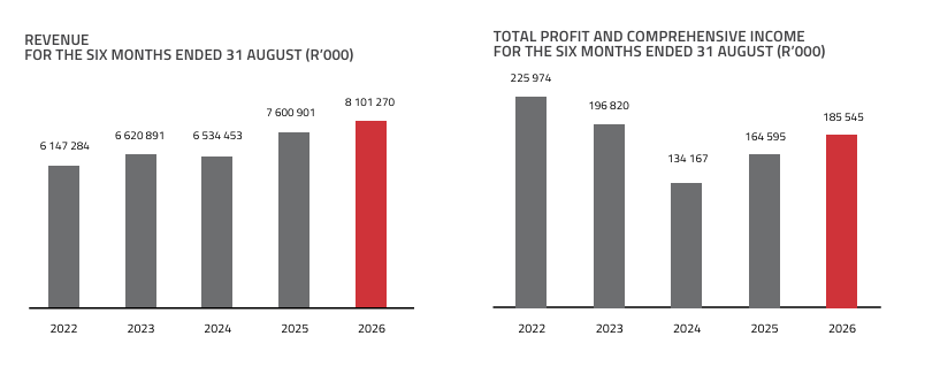
Revenue increased by 6.6% and operating profit was up by 13.9%, so that’s an elegant example of operating leverage. The group’s operating profit margin improved from 4.3% to 4.5%.
There’s more leverage as you work further down the income statement, as HEPS increased by 18.6%.
CMH is one of those companies with a fairly steady revenue profile and an erratic earnings trend. To their credit, they make it very easy to see this with these charts:
Now, that all sounds like a relatively easy period and a set of numbers that will help shareholders sleep at night. But as we read the commentary, we find some very interesting stuff.
Firstly, you’ll find an incredible statistic: the Chinese brands have seen their share of national sales rise from 14.8% to 20.0%. It’s rare to see such accelerated disruption.
In management’s words:
“With the proliferation of products and brands – and increasing each quarter, it is impossible to identify all the potential long-term winners.”
Ain’t that the truth?
It feels like barely a month goes by without a new brand entering the market.
The sobering comments continue, with CMH noting that many of the importers are overstocked with unrealistic expectations in the market. This is leading to very thin margins, with the variable volume incentives and bonuses being “virtually the only retained gross”.
In other words, when you look at those heavy discounts at the traditional car brands (like the ones I’ve seen at Volvo), you aren’t going crazy for wondering how anyone is making any money.
Here’s another fascinating comment from CMH that I’m going to repeat verbatim:
“The used car market has proven to be particularly difficult. The influx of Chinese/Asian brands that were introduced into the market at discount prices some four to five years ago are now at the recycle stage. However, the sharp depreciation in value of these vehicles has surprised owners and forced them to hold on for longer, until the trade-in values align with the residual amounts owed to banks.”
Put differently: people buying Chinese cars on a gazillion-year finance deal with their first-born child pledged as the residual security are going to have a bad time. But those people will only find that out a few years from now.
The real issue is that buyers of legacy brands (other than the really big ones) are experiencing the same problem anyway thanks to the accelerated depreciation caused by Chinese disruption, except their problems started at a higher price point.
This is causing a lot of pain in used car sales. CMH’s group unit sales in the used space were down 10%, while gross margin fell by 4.7%.
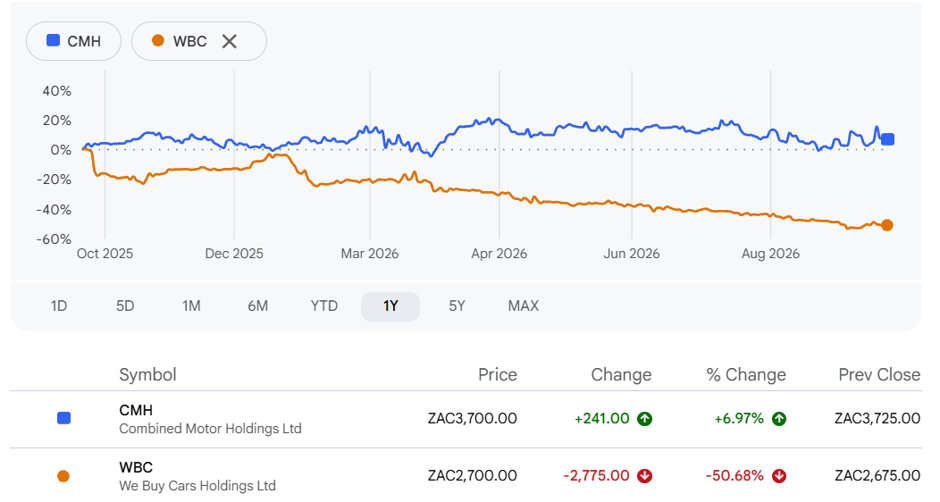
This is a very negative near-term read-through for WeBuyCars (JSE: WBC) of course, although the market already hates the stock these days:
In case you’re wondering, I still hold WeBuyCars as a long-term play. I’m not sure we’ve seen the bottom yet, hence I’m waiting before I buy the dip of all dips.
My thesis on it is pretty simple: if it’s tough out there for all used car dealerships, then market consolidation and the survival of the fittest is a likely outcome in a super fragmented market.
The fittest (in my opinion) is the biggest, most data-pregnant option in the used car market.
That’s WeBuyCars.
Going back to CMH, the aftermarket parts department is struggling to maintain high levels of availability. This is another cautionary tale for anyone buying one of the obscure Chinese names, with CMH referring to “volatile demand and erratic supply chains”.
Some of this could just be teething issues of course, but I’ve seen plenty of online debate around parts availability (or lack thereof) for some of the Chinese brands.
CMH notes that the brands like Nissan, Volvo and Land Rover are experiencing declining workshop labour sales. This is important insight into how the business model falls over entirely for such brands: when sales dry up in year 1, the workshop feels it for several years.
All of this sounds so negative, so how did CMH do well?
You wouldn’t look at the numbers for the motor retail / distribution segment and conclude that CMH is struggling. Revenue grew by 6.3% and gross profit looked steady at 13.3%. Operating margin improved from 2.7% to 3.0%.
This means we have an intoxicating mix of CMH making good money from the Chinese brands, while also painting such a sobering picture of that market.
I always enjoy highlighting the structurally different margins in the car hire business. Revenue there was just R415 million vs. R7.6 billion in motor retail / distribution, yet the operating profit is much closer: R145 million vs. R223 million. That’s what happens when operating profit margin in car hire is 35% vs. just 3.0% in the motor trade!
The financial services business has also done very nicely in this period. It’s a small value-added service, but a profitable one. Thanks to the performance in areas like insurance, operating profit in that segment increased from R22 million to R30 million.
Overall, this is a rare example of a totally different tone in the narrative vs. the numbers. That makes me question how sustainable the meteoric rise of the Chinese brands really is.
A number of large updates needed to carry over to tomorrow to allow space for CMH, but I’ve covered a few shorter updates from the last couple of days below.
Calgro M3’s cash conundrum (JSE: CGR)
You won’t find fireworks at the top of the Calgro income statement for the six months to August 2026. Revenue increased by just 1.2%.
The residential property development segment is responsible for nearly 90% of group revenue. This segment experienced a revenue decline of -0.6%, anchoring the group to a flat performance despite the best efforts of the Memorial Parks segment (up 20%).
Gross profit margin in Residential Property Development ticked up from around 26.3% to 26.6%. It may not sound like much, but it’s something. Importantly, this remains above the group target of 20% to 25%, so there’s risk to the downside for gross margin in the core business.
The gross profit margin in Memorial Parks is much higher than Residential Property Development, coming in at 54.8% (vs. 50.4% in the comparable period). This is why the group gross profit margin was 29.5%, well above the level achieved in the Residential Property Development segment.
There are still question marks around the long-term economics of the Memorial Parks. But for now at least, it’s a useful source of cash for the group that helps balance some of the swings that a property developer can experience. More on that to come.
The problem is that with such limited revenue growth and a largely flat gross profit margin at group level, there wasn’t much of a buffer against the impact of rising operating costs. Sure enough, HEPS fell by 4.8% as the limited top-line performance filtered through the income statement.
In terms of the balance sheet, the group is currently rationalising its base of projects by disposing of non-core assets. There are various stages of completion here, as some of the properties are in the process of getting the correct rights or infrastructure in place, so the company reckons it needs five years to get all the disposals done.
This length of time and the complexities involved in offloading assets could be used by bears as partial justification for the discount to net asset value per share. A marketability discount exists for a reason, as it takes time in the real world to crystallise a sale of assets.
Still, Calgro’s net asset value per share of R17.21 is in a different postal code to the share price of R3.75. There’s a lot more to that discount than just the marketability of non-core assets. I suspect that the cash profile plays a big role here.
And this brings us neatly to the problem: cash utilised in operations deteriorated from R50.6 million to R110.3 million i.e. the business absorbed more than double the amount of cash that it did in the prior comparable period.
Once you take into account the finance costs paid, you’ll find that net cash utilised from operating activities was a whopping R159 million. They had to raise more debt to help fund the deficit, with cash and cash equivalents at the end of the period of just R52.3 million vs. R163 million a year ago.
Why did this happen?
It looks like the installation of infrastructure at the BDC project is to blame. Such is the joy of being a property developer: huge cash has to be sunk into the ground before you actually see a return. It’s a feature of the business model, not a bug.
At least the sectional title activities at Scottsdene, South Hills and Belhar should be completed in the latter half of the year, with 60% of the units having finalised guaranteed off-take agreements. That derisks the cash position to some extent, but there are still some scary numbers here for investors to consider.
For example, as great as it is that net debt to equity is still at a decent level, the bigger worry is that the debt service cover ratio of 1.35 isn’t particularly far above the covenant level of 1.2.
Management was on Unlock the Stock this week. The YouTube recording is now available, with a particularly vibrant Q&A that focused on the cash topics:
Oversubscribed capital raise at Fairvest (JSE: FTA | JSE: FTB)
As expected, Fairvest had absolutely no problem raising fresh equity capital. Demand was strong enough that the company ended up raising more than planned.
But the extent of the increase in the raise is quite something to behold.
Having planned to raise R500 million in new B shares, the company eventually raised R1.25 billion at a discount of just 2.7% to the 30-day volume-weighted average price (VWAP).
And get this: the book was still oversubscribed even at this level!
The JSE is a very exciting place for property companies, but investors must always be wary of things getting too hot in this space.
But not all the property counters achieve a premium valuation. Small and obscure names still find it tougher to raise capital and get much attention, making a potential delisting all the more likely.
A suite of mining updates: BHP (JSE: BHG), Anglo American (JSE: AGL), Kumba Iron Ore (JSE: KIO), DRDGOLD (JSE: DRD) and Tharisa (JSE: THA)
Starting with the quarterly activities report at BHP, full year guidance is unchanged across the board. This tells us that things have been largely in line with company expectations.
But this doesn’t mean that production went up!
For example, copper production fell by 19% year-on-year, driven by planned grade declines and scheduled maintenance, as well as other factors like the weather in Chile and various operational challenges. That’s a pity, as copper prices were 53% higher than a year ago.
Bulk commodities did well despite maintenance in this quarter, with Western Australia Iron Ore (WAIO) setting records at the mine and port with production growth of 4% year-on-year. Iron ore prices were down 9% in USD terms though, so they certainly aren’t enjoying the pricing tailwind that we are seeing in copper.
Steelmaking coal grew production by 1% and enjoyed a price increase of 34% year-on-year.
Energy coal production jumped by 26% at a time when prices were up 23%, so that’s very encouraging.
The investment in potash is getting closer to fruition, with stage 1 of the Jansen project now 87% complete.
Then we have another big name in the sector: Anglo American. The geographical profile of the group means that the winter weather in Chile has played a role here as well. Still, Anglo is also on track to meet their FY26 guidance, with copper ore grades expected to improve in the final quarter of the year.
I’ll deal with the so-called “simplified portfolio” first. Year-to-date copper and premium iron ore dipped by 1% and 3% respectively, while manganese ore production increased by 31%. If we isolate the latest quarter, copper and premium iron ore fell by 5% and 4% respectively, while manganese iron ore was up 6%.
Moving on to the businesses that Anglo American is getting rid of, we find a 4% year-to-date increase in steelmaking coal production. The quarterly jump is much higher at 53%! The sale of steelmaking coal to Dhilmar is on track to complete by the first quarter of 2027.
The nickel business saw production decline by 3% year-to-date and increase by 3% for the quarter. The group is currently working through the EU regulatory approval process to sell that asset.
And then the bright, shiny elephant in the room: De Beers.
Production is up by 22% year-to-date, so I think the game is up in terms of mined diamonds being rare things. Having said that, production was down by 11% in the latest quarter due to planned maintenance and a slowdown ahead of the previously announced production pause.
They really are trying everything here, but diamond prices just keep dropping.
Very few people have the money or the interest in mined diamonds vs. identical lab-grown alternatives at a fraction of the price.
Anglo says that the company continues to “work towards a transaction in a challenging market, having taken decisive action to protect cash and preserve value” at De Beers. Disruption is a helluva thing.
Next up is Kumba Iron Ore, part of the Anglo stable. Total production fell by 19% year-on-year due to the temporary shutdown of the Sishen dense-media-separation plant.
I really hope that nobody ever refers to me as dense media!
Thanks to the levels of finished stock at the ports, sales increased by 3%. Finished stock has now declined from 7.0 Mt to 4.8 Mt. They were able to successfully absorb the impact of lower production.
It really says a lot about our rail infrastructure in this country that Kumba has to carefully manage the difference between stock at the mine and stock at the port. Case in point: ore railed to port declined by 8%, largely driven by a derailment that impacted volumes.
Export iron ore prices didn’t play ball this quarter, impacted by Chinese steel mill profitability challenges. Kumba is still achieving a premium to the benchmark price due to the quality of its premium product, but the year-to-date decline in dollar pricing is 6%.
Cost guidance for the year is unchanged, with Sishen expected to be at the upper end of the range and Kolomela expected to be at the lower end.
Onwards to DRDGOLD and an operating update for the quarter ended September 2026, a period in which the average gold price received increased by 14% on a year-on-year basis.
It was down by 6% sequentially though, so there’s plenty of debate around where the gold price might go from here.
DRDGOLD can’t control the price, but it can control production. Gold production increased by 10% year-on-year and 2% sequentially, in both cases supported by improving yield despite a decrease in tonnage throughput.
Sales can deviate from production, with gold sales up 14% year-on-year and flat sequentially. This led to a 31% increase in revenue year-on-year, but a 6% decline sequentially.
Cash operating costs were driven by higher input costs like diesel, as well as increased purchasing and processing of higher-grade third-party material. Electricity and labour costs are always a factor as well.
Overall, operating costs increased by 12% year-on-year and 6% sequentially.
Add it all together and you’ll find incredible variance in operating profit depending on which base period you use. On a year-on-year basis, operating profit was up by 42%. But sequentially, it fell by 14%.
Operating leverage essentially amplifies the change in the gold price, leading to bigger swings in operating profit than in the underlying commodity.
The company is in a significant capex cycle at the moment, with various Vision 2028 projects underway. Growth capex was very high in the quarter ended June (R1.16 billion), so the latest quarter looks tame in comparison at R556 million (down 52%). Growth capex is also down 29% year-on-year.
Sustaining capex tells a different story though, up 22% sequentially and 132% year-on-year.
The group remains debt free despite all this capex. They have access to bank financing, but for now the R2.45 billion on the balance sheet is adequately supporting the business.
For context, the free cash inflow in this quarter was R725.8 million, benefitting from solid profitability and relatively lower growth capex.
DRDGOLD has reaffirmed its FY27 production and operating cost guidance.
At Tharisa, the first wheeled renewable energy from Etana Energy was received in September 2026. This will meet roughly 10% of the Tharisa Mine’s current monthly electricity demand.
That’s obviously good news for the reduction of energy costs and the improvement of environmental metrics.
There’s more to come, with Etana Energy forecast to supply 70% of Tharisa Mine’s current electricity demand over the long term.
I must point out that these percentages relate only to the open pit operation, not the planned underground project which is expected to double the operation’s electricity demand.
Always do your own research and do not treat anything you have read here as financial advice.
Primary Health Properties is to form a 50:50 strategic joint venture with Singapore’s GIC to invest in private hospital infrastructure. PHP will seed to the JV 27 private hospitals valued at £0,7 billion from its portfolio. This will yield the company £0,5 billion in net cash proceeds which it intends to use to reduce debt from the Assura acquisition. PHP retains a 50% stake and will serve as property manager. The expected completion of the transactions is November 2026.
Putprop announced its intention to repurchase 13,545,666 ordinary shares (31.94%) from minority shareholders via a scheme of arrangement. This excludes those shares held by the Carleo Group and other minorities holding 28,86 million shares. The deal, at R9.00 per share in cash, puts the transaction value at R121,9 million. Following the implementation of the scheme the company will be delisted from the Main Board of JSE. Reasons given for the take private of the company include the recurring regulatory and compliance costs associated with the listing.
Famous Brands is to reduce its exposure in Botswana with the sale of a 21% stake in Retail Group to its Botswana partners. The company will retain a 30% shareholding in the holder of many well-known restaurant brands. The disposal is part of the company’s capital-light expansion approach which is aimed at reducing direct exposure to operating losses stemming from difficult economic conditions in Botswana.
Following shareholder approval in August 2026, enX confirmed this week that it received its final compliance certificate from the Takeover Regulation Panel, allowing the final phases of implementation to proceed. In June enX announced the sale of the New Way Power business along with its associated manufacturing site to GPR South Africa for a purchase consideration of R220 million.
Unlisted Companies
Stirling Square Capital Partners, a pan-European mid-market private equity firm, has through its portfolio company Sustainable Agro Solutions, acquired a majority stake in Afrikelp. Specialising in the harvesting, research, production and distribution of seaweed- and plant-based biostimulants, Afrikelp is one of the world’s leading producers with applications across more than 45 crops including fruits, vegetables and row crops. Financial details were undisclosed.
Shree Property, a private family-owned development group has acquired two prime sites in the South Durban Industrial Basin. The properties acquired from Tiger Brands and Plascon will be, with an investment of c,R1,6 billion, developed into new logistic warehousing.
Metals One, a mineral exploration and investment company, is to acquire Lions Bay Resources, a South African gold mining and power infrastructure company, in an all-share transaction valued at £6,5 million. Metals One will first raise its stake from 30% to 49.99% by exercising an existing option, and then the company acquire the remaining 50.01% from shareholders Lions Bay Capital and Salamander Consulting.
Movement Software, headquartered in Sweden has acquired Freeway Fleet Systems, a fleet maintenance and asset management software supplier headquartered in Johannesburg and London. The acquisition extends the group’s presence in Southern Africa and in other international markets. Financial details were not disclosed.
Fairvest has raised R1,25 billion via an accelerated book build which, at this level, was oversubscribed. The company will issue 185,185,185 new B shares at a price of R6.75 per share which represents a 2.7% discount to the 30-day VWAP of the B share of R6.94 per share. Initially the company aimed to raise R500 million. In April the company undertook a capital raise of R900 million, issuing 130,43 million shares at R6.90 per Fairvest A share – a 5.5% premium to the 30-day VWAP at the time. Fairvest intends to use a component of the funds to close on strategic acquisitions currently under negotiation.
Datatec returned R7,05 billion to shareholders through a special cash dividend and a scrip distribution alternative. The company issued 94,32 million shares at R50.63 per share resulting in a capitalisation of distributable retained profits of R4,78 billion while shareholders holding 78,59 million Datatec shares opted for the special cash dividend of R29.00 per share resulting in a distribution of R2,28 billion.
Following the results of the scrip dividend election, Fortress Real Estate Investments will issue 19,451,831 new Fortress B shares in lieu of a final dividend, resulting in a capitalisation of the distributable retained profits in the company of R466,8 million. The shares were based on a reinvestment price of R24.00per share.
In September Shuka Minerals agreed to the assignment of c.£800,000 of its Gathoni Muchai Investments (GMI) Convertible Loan to several strategic investors. The restructuring reduced the company’s immediate debt burden, bringing in long-term capital backing for its flagship asset. An Australian investor has elected to convert a £63,334 loan into to 1,583,352 new ordinary shares at a conversion price of £0.04 per share. Separately the creditor has agreed to the settlement of an outstanding invoice of £61,000 through the issue of 1,525,000 new ordinary shares at a price of £0.04 per share.
Europa Metals listed on the ASX on 16 October 2026, with its IPO raising A$4 million. The funds raised will be used for an initial exploration programme across three priority projects in Austria.
This week the following companies announced the repurchase of shares:
South32’s extended repurchase programme commenced in September 2026. The company will, in total, acquire up to 4,49 billion shares with a proposed buyback end date of 10 September 2027. This week the company repurchased 1,380,655 shares for an aggregate A$6,01 million.
Reinet Investments commenced its 7th share repurchase programme, for up to an aggregate maximum amount of €250 million subject to a maximum of 8 million ordinary shares over a period ending on 15 December 2026. The shares will not be cancelled. During the period 12 to 16 October 2026, the company repurchased 572,869 shares for an aggregate R254,91 million.
In March 2026, Quilter commenced a £100 million share buyback programme, to reduce the share capital of the company and return capital to shareholders. The third and final tranche of the programme commenced on September 8, 2026, with repurchased shares to be cancelled. During the period 12 to 16 October 2026, Quilter repurchased 755,902 shares on the LSE with an aggregate value of £1,34 million.
In June 2026, Greencoat Renewables announced its intention to commence a second tranche of the repurchase programme to return a further €25 million of capital to shareholders. The second tranche repurchase will be complete by end-December 2026. This week 664,204 shares were repurchased for an aggregate €529,616.
During the period 12 to 16 October 2026, Prosus repurchased a further 2,303,676 Prosus shares for an aggregate €82,77 million and Naspers, a further 665,075 Naspers shares for a total consideration of R476,62 million.
Ninety One plc announced an increase in the repurchase programme from £30 million to £55 million. The shares, to be purchased on the open market, will be cancelled to reduce the Company’s ordinary share capital. On the 16 October 2026, the company repurchased a further 644,144 ordinary shares on the LSE at an average price 203 pence per share for an aggregate £1,31 million and 181,476 shares on the JSE at an average price per share of R44.42 for an aggregate R8,06 million.
British American Tobacco has again extended its share buyback to end on 23 December 2026. All shares repurchased will be cancelled. Over the period 12 to 16 October 2026, the company repurchased a further 658,415 shares at an average price of £43.02 per share for an aggregate £28,28 million.
Anheuser-Busch InBev’s US$6 billion share buy-back programme continues. The shares acquired will be kept as treasury shares to fulfil future share delivery commitments under the group’s stock ownership plans. Over the period 12 to 16 October 2026, the group repurchased 364,696 shares for €25,99 million.
Two companies issued profit warnings this week: Finbond and Pick n PayStores.
Three companies announced, renewed or withdrew cautionary notices: Putprop, Mahube and ArcelorMittal South Africa.
Eos Capital has announced the completion of a partial exit from Namibia’s Kadila Poultry Farming through its Euphrates Agriculture Fund. Euphrates, along with Africa Venture Partner Projects and Oyeno Poultry Industries, backed Kadila in 2024. The early-stage capital helped build Kadila’s state-of-the-art production facilities and take the business from concept to full commercial operation. The partial exit delivers a 19% IRR and 1.4x money back to the Fund’s investors.
Helios Investment Partners announced that Helios Fund V has entered into an agreement to acquire up to a 49% interest in Stratton Africa Holdings Limited, the Mauritius-incorporated holding company of Merec Industries, from Invictus Investment. Merec is Mozambique’s largest flour milling company, processing wheat and corn into an integrated product portfolio spanning flour, pasta, biscuits and animal feed. Its mills, production facilities and silos are strategically located in each of Mozambique’s three principal port regions: Beira, Maputo and Nacala – making it the only miller with manufacturing facilities in all three. Merec also owns a grain terminal at the port of Maputo. Financial terms were not disclosed.
Kong Solaire SAS, a project company owned by Africa Via, Axian and the Private Infrastructure Development Group (PIDG) through InfraCo, have signed a financing agreement with FMO, the Dutch entrepreneurial development bank, for the Kong solar photovoltaic power plant in Côte d’Ivoire. FMO is providing the project’s entire long-term financing, amounting to up to €55,5 million, with a 20-year tenor. The financing incorporates adaptations to conventional project finance structures to reflect the specific context of emerging markets in West Africa, developed jointly by the parties. Located near the town of Kong in northern Côte d’Ivoire, the solar power plant will have an installed capacity of 50 MWp. Its annual output is expected to reach approximately 96 GWh, which will be fed into the national electricity grid. This generation is expected to supply electricity to approximately 240,000 people and avoid 54,000 tonnes of CO₂ emissions per year.
Tactful AI, an Egyptian startup specialising in agentic AI-driven customer experience (CX) infrastructure, announced that Hatem Dowidar, former Group CEO of e&, has joined its investor roster through a direct investment in the company’s Pre-Series A extension round. The financial terms of the deal were not disclosed. Tactful AI develops an agentic AI-powered customer experience platform that enables businesses to manage customer interactions, automate workflows and analyse conversations across multiple channels. The company is preparing to introduce next-generation agentic AI technology that will allow enterprises to build and modify customer experience workflows in hours rather than months while maintaining human oversight and approval processes.
Fortis Green Renewables Investment Management and Zeitinger Invest have invested in the GRIPS Energy Group, a developer, owner and operator of commercial and industrial solar and battery energy storage projects across Sub-Saharan Africa. The investment finances the acquisition of operational renewable energy assets in Senegal, Botswana, Zambia and Uganda and provides growth capital to support GRIPS’ expansion of distributed solar and solar-plus-storage projects serving commercial and industrial customers.
Camco-managed REPP 2 has provided a €12 million senior debt facility to Afreenergy Solar to refinance an operating portfolio of rooftop solar assets and fund the construction of new solar PV and battery storage projects for established commercial and industrial customers in Senegal. The REPP 2 financing will support the expansion of Afreenergy Solar’s portfolio from 2.7 MWp to 14.9 MWp of rooftop solar PV capacity, alongside 5.7 MWh of battery storage, avoiding approximately 21,300 tCO₂e annually. The portfolio will provide customers with more reliable electricity, reducing exposure to grid interruptions and supporting more resilient industrial and commercial operations.
Egypt-based proptech startup Aqar Exit has secured a US$200,000 (EGP10 million) investment from businessman Ayman Mamdouh Abbas, executive chairman of Intro Holding Group, in exchange for a 10% stake, valuing the company at approximately $2 million (EGP 100 million). Aqar Exit operates a platform for transferring property purchase contracts, targeting buyers who are struggling to meet instalment obligations on their real estate units. The platform connects these sellers with prospective buyers seeking properties at their original contract prices, without paying additional premiums, commonly known in Egypt’s property market as overprice. Under the company’s model, sellers can seek to recover the amounts they have already paid towards their properties without incurring contract assignment fees.
Nordic Impact Funds has invested an undisclosed sum in Uganda’s Irrisol Engineering. This follows the investment announcement by DOB Equity in early September. Irrisol is a water infrastructure company providing safe, reliable and affordable water to underserved rural and peri-urban communities in Uganda through solar-powered water systems. Irrisol designs, builds and operates solar-powered water mini-grids across Western Uganda. The systems deliver water directly to households and community taps, combining solar-powered pumps with consumption-based billing and mobile-money payments to make access to water more reliable and affordable.
Egyptian fintech MNT-Halan began trading on the Egyptian Exchange (EGX) on 20 October 2026 following an initial public offering that saw strong demand from institutional and retail investors. The IPO involved the sale of 320 million existing ordinary shares, representing 20% of MNT-Halan’s issued share capital, by existing shareholder MNT Investments B.V. The offering comprised 272 million shares allocated to institutional and other private-tranche investors and 48 million shares allocated to retail investors. The private tranche was 11.2 times oversubscribed, rising to 19.4 times excluding cornerstone investors, while the public tranche was 43.6 times oversubscribed, attracting more than 41,500 subscription orders.
Oryx Energies announced that it had signed an agreement with Amsons Group for the sale of its downstream oil business in Tanzania. The transaction forms part of Oryx Energies’ ongoing strategic review of its portfolio of downstream assets in Africa. Amsons Group is a diversified Tanzanian business group with an established presence in the region. The transaction marks a significant milestone in East Africa’s downstream energy landscape, transferring key retail service stations, storage terminals, and distribution infrastructure into local hands. Financial terms were not disclosed.
Aliko Dangote confirmed that his company had acquired a 25% stake in Kenya Pipeline Company in a deal valued at approximately US$327 million. The stake was acquired to facilitate the distribution of petroleum products. Earlier this year, Kenya sold a 65% stake in Kenya Pipeline Company through an initial public offering, in a major privatisation move aimed at raising government revenue amid limited fiscal space.
For more than 25 years, Satrix has helped South Africans access local and global markets through ETFs. Now, the business is taking that expertise beyond the country’s borders, with listings in Namibia, Botswana and Kenya as it works to bring simple, low-cost investment solutions to a new generation of African investors.
In this episode of the Ghost Stories podcast, The Finance Ghost is joined by Duma Mxenge, Head of Business and Market Development at Satrix, to unpack the opportunities and challenges of expanding ETFs across the continent.
From navigating regulations and market infrastructure to understanding what investors in different African countries actually want, Duma shares insight into the work being done behind the scenes to build deeper, more accessible capital markets.
We also explore why demand for global exposure is often stronger than demand for local equity products, whether an Africa-focused ETF is realistic any time soon, and what the future may hold for cross-border investing on the continent.
In this episode, we cover:
Why Satrix believes the time is right to expand beyond South Africa
The journey from initial research in 2019 to listings in Namibia, Botswana and Kenya
Why African investors are increasingly looking for global market exposure
The popularity of products tracking the S&P 500, MSCI World and Nasdaq 100
How ETFs can help deepen African capital markets
The regulatory, liquidity and operational challenges of cross-border ETF listings
Why institutional and retail investors are responding differently to these products
The importance of education, distribution and local partnerships
Whether an Africa-wide equity ETF is a realistic prospect
Alternative ways for South African investors to gain exposure to growth elsewhere on the continent
The role Satrix hopes to play in building Africa’s investment ecosystem over the coming decades
Transcript:
00:00 Intro
01:00 South Africa is the track record, Africa is the opportunity
02:14 Satrix’s strategy to address ETF demand in Africa
04:21 Listings in Namibia, Botswana and Kenya
07:00 Institutional vs. retail investors
08:16 Demand for developed vs. emerging market funds
10:28 Financial markets infrastructure to make this possible
14:01 How far off is the “Africa Basket” ETF?
18:26 Closing thoughts
The Finance Ghost: Welcome to this episode of the Ghost Stories podcast. Today, we will be talking about how Satrix is spreading its wings across Africa. It’s something I am really looking forward to because I think ETFs have played such an important role in just giving access to South Africans to both local and global markets. ETFs really do make it easier to invest.
And who better to speak to today than Duma Mxenge? He is the Head of Business and Market Development at Satrix. Duma, thank you so much as always for joining me. Always fun to chat to you and particularly, I think, on this topic. This is going to be interesting.
Duma Mxenge: Thank you, Ghost, and thank you for having me. I’m really excited to talk about the Africa expansion, looking beyond South Africa.
The Finance Ghost: Yeah, absolutely. That’s the point here, right? Satrix has already done so much in South Africa. You guys literally pioneered the ETF industry and there have been a few podcasts that we’ve done before with the team from Satrix that have really made that point clear.
And now, it’s time for the rest of the continent, hey? I’m going to sound like Shakira here: “It’s time for Africa!”
So, what is happening? Why do you believe that there’s an opportunity here? Why do you believe the timing is right?
Duma Mxenge: As you said, Satrix has been around for… it’ll be our 26th year this year. And through that journey, I think what people underplay is the powerful and important role that an ETF plays. I know you’ve said that Satrix has pioneered, which is true, but it’s not just us. There are a lot of partners in the ecosystem who have actually made this possible.
I think we are at that stage now, where we’ve looked at the growth and adoption rate in South Africa across all segments, that there is value in replicating that in other markets. We can touch on those markets, but again, it’s basically for us to reset as a team, build new partnerships, build new relationships and also take a long-term view in terms of the growth of ETFs.
But as we see it, ETFs can play a meaningful role in terms of deepening capital markets across Africa.
The Finance Ghost: So, I’m curious. Are you taking a product to the people in Africa that you believe they need, or have people been asking for this? What’s been the genesis of this decision to go beyond South Africa now? Is there a real need out there? Is there a hunger on the continent for this stuff?
Duma Mxenge: So, the journey actually started in 2019, just on the back of us listing our global ETFs on the JSE. We saw the excitement in terms of, for once now you could have ETFs that give you global exposure priced in rands, that are listed on the JSE, which are actually well priced.
And we thought that could be quite an interesting proposition, just purely from a product perspective. But as I said, from 2019 we didn’t go out and just put out a product. We engaged the market. We tried to understand different markets.
So, the markets we looked at were Namibia, Botswana, Kenya and Nigeria.
Part of it is the interest. Secondly, who would buy it. And thirdly, also just interacting with the various exchanges, the regulator, and getting an understanding of what would work.
And now across the board, because we thought as a start, we’d do exactly what we did in South Africa and actually list the Satrix Top 40 – so, Africa for Africa – but the need in these markets was, and still is, that they want global exposure.
Not only just for institutional clients, but also the retail clients who are struggling to access offshore strategies because of FX and having to list offshore, and also, the Know Your Customer (KYC) was quite onerous. So, that’s where the journey for us started. That was from 2019.
The Finance Ghost: Yeah. These things tend to be several years in the making, right? So, in reality, I guess the journey started 26 years ago, as you say, then in Africa, 2019, pre-Covid. And here you are today. You’ve mentioned a few countries, but let’s just get a bit closer to that detail.
I think what’s important for people to keep in mind is that ETFs, if you think about them, can work in two directions, right? You could be taking African assets to a broader investor base – for example, on the JSE you could list a basket of African stocks (I doubt the liquidity is there, but that’s the one direction it could go in). Or it could be the other way around (which I think is what you’re doing here), which is taking global assets to an African investor base.
Duma Mxenge: What we’ve decided to do is to provide global assets in the respective countries. So, currently we have listings in Namibia – in fact, we have about five listings in Namibia. We’ve just recently listed in Botswana – it’s three listings, and I’ll share what those strategies are. And then we only have one listing in Kenya, which is the MSCI World.
So, in Botswana it’s three global strategies: the MSCI World, the Emerging Market (EM), as well as the NASDAQ 100. In Namibia, as I said, it’s five listings, so we’ve got the MSCI World, we’ve got the EM, we’ve got NASDAQ 100 and we also have the S&P 500. And what’s different in the Namibian market is that we also have regional exposure. So, we’ve got a Satrix Namibian Bond, which we can touch on.
But the strategy and what we really want to deepen is firstly, to make sure that we get the global assets right, even from an investor experience – the spreads, the liquidity, the education, the distribution and the partnership. So that’s the heavy lifting we’re doing at the moment.
Listing the product is one part of it. The other big part that we need to get right is the distribution and adoption in these respective markets, before we can actually look at any new products to market locally.
The Finance Ghost: Yeah, 100%. And I would imagine it’s a lot of the same things that have contributed to growth in the South African market, right? So, investor education would be one – access to these assets and understanding what’s there and that the stuff is available.
And, of course, it’s nice and low cost, right? I’m sure that that element of the Satrix offering has been carried through into these new products.
Duma Mxenge: No, absolutely. Again, to your point, there are also other reasons as to why you actually want to list in these markets. For example, in South Africa, what has also helped the adoption rate of offshore is the Reg 28. So, reading the regs and understanding what it entails and what sort of exposure you can actually get is very important.
For example, if you look at a market like Botswana (and it’s the same in Kenya), listing on their local exchange, you get local asset status. This then entails that instruments that are listed on their local exchange (in Botswana’s case, they’re priced in pula) will be deemed to be local, albeit on a look-through basis it still applies for institutional clients. In Kenya, once you are listed in-country, priced in Kenyan shillings, it breathes and it lives like a local asset.
And if you follow the western and eastern markets in Africa, what you will find (which is quite unique from the southern tip of Africa) is that a large majority of the exposure, even for institutional clients, is fixed income.
So now, we are bringing equity strategies which are deemed to be local that provide the growth assets that a lot of the investors have been looking for in those markets.
The Finance Ghost: And in terms of the feedback on the ground, I would imagine that it’s a mix of retail investors and institutional investors. Where is the focus at the moment?
Duma Mxenge: Look, in terms of volume and base it’s definitely institutional, but I guess in terms of adoption and excitement, it’s retail. It was exactly the same here in South Africa when we started with the Satrix Top 40. And so, what we see across the board is great activity in terms of retail clients embracing it, because it’s a novel idea, especially if you don’t have any offshore products that you can access.
We got great feedback from Botswana to say, “For once, now, we can actually access the Nvidias of the world and the Apples of the world locally, in pula.” And the same thing applies in Kenya.
Where I think a lot of the education and trust still needs to come is more on the institutional side, so we’re doing a lot of work on that end. And it’s not just the product, per se. It’s also understanding a little bit more, in terms of what distribution looks like, the go-to-market strategy, the importance of partnership and also the localisation of the product. So, there’s a lot of work we’re doing, from a marketing perspective, to get that right.
But we’re super optimistic. We’re super excited about these markets, because we’re coming off a lower base and the demand is real. And I must say that both the exchange and the regulators have been super supportive.
The Finance Ghost: And out of interest, are you finding that the demand is stronger for the traditional, offshore-type plays? Or is it more… you mentioned an emerging market fund there, so are people looking for developed market exposure to diversify the fact that they live and earn and have been investing in a place like Botswana, or are they open to emerging markets as well? Where does the interest lie?
Duma Mxenge: Yeah, it’s been quite interesting. We were actually chatting about this as a team. Namibia is different. It lives and breathes like South Africa, so they understand the MSCI World a lot better, and EM, and also the combination of the two.
But our engagements in Botswana, as well as in Kenya, show that there seems to be a great interest for the S&P 500 – so basically, exposure into America – which I found to be quite interesting. I guess it’s the orientation, globally, and America’s got a very good brand. So, when I see retail clients, specifically from a flow perspective, a large majority of the flows that we’re seeing is actually the S&P 500.
That being said, for institutional investors, as you know, the world is global, so is having exposure into EM. And it also helps that EM has actually done well, from a performance point of view. We are seeing flows on that end, albeit largely driven by the performance of that region or with exposure, but I think, over time, there’s also going to be a greater appreciation of what EM brings into someone’s portfolio.
The Finance Ghost: Yeah, I think people tend to be attracted to the big, exciting names in AI, etcetera, and obviously, those are mainly found on the S&P side. Although, if you dig and you go look in emerging markets, you’ll find some pretty interesting exposures, often further up the value chain, or adjacent stuff. It’s really interesting. It’s all the work that we try and do on this podcast to just show people the breadth of ETFs, right?
Duma Mxenge: Absolutely. Your podcast also plays a pivotal role, in terms of getting that right. What I also love about ETFs and the transparency, the ease of understanding, is that porting that education is a lot easier than when you have these complex strategies where different markets don’t understand it because it’s not consistent.
Whereas in this case, I guess for us, the big job that we need to do is more the plumbing, the distribution, the understanding of the wrapper and what an ETF is. And I think, once people understand that and they’re comfortable with it, we should see great adoption in those markets.
The Finance Ghost: Let’s talk about the plumbing then, which allows you to actually expand into Africa. You raised it earlier in the podcast when I mentioned the pioneering approach that Satrix has taken to ETFs in South Africa. As you’ve correctly pointed out, it’s obviously not just you guys, there’s a whole ecosystem that has to be built around it.
I would imagine there have been a number of hurdles that you’ve had to jump over to actually get the compliance stuff right, the regulatory stuff right, all of the approvals, dealing with the exchanges (because obviously these are exchange-traded products, I mean, that’s what the E and the T stand for).
So, perhaps you can just give us an idea of this expansion into Africa and some of the issues you’ve had to overcome? Obviously, to the extent you can share.
Duma Mxenge: Yeah, look, I mean every market is different and every market runs their infrastructure differently and there’s a good reason behind it. And again, as we said, we started in 2019. That’s not to say we immediately started listing ETFs. There’s a lot of understanding of what that market is trying to achieve.
For example, there had needed to be greater appreciation, not just the FX (meaning, you have to convert rands into pula), but who’s actually going to be your FX provider? You need to get that right.
Also, each market has its own playbook. If you’re going to come to this market, there needs to be greater local industry players. And we get it. That’s part of deepening the knowledge and expertise, and also the capital market, as I said.
And so, within that, there are probably four areas or layers of plumbing that one needs to think about. It’s basically the market quality or liquidity. What does that mean? You talk about two-way pricing and making sure that the spreads are in keeping. You need to think about what role your local provider will play in-country and how they get connected with our primary market maker who’s based in South Africa, making sure that their experience is almost the same as in South Africa. So, the liquidity piece is very important.
And when we talk about liquidity, it’s not just the availability of the instruments. It’s making sure that the segment market is thriving (so, local brokers need to be playing that market), and that the private market is thriving as well. That’s a big consideration.
The other big consideration is, yes, getting the regs right, but obviously, continuously making sure that, from a compliance point of view, you’re in lockstep with the respective countries.
And the tax treatment is different. What we’ve done in order to make sure that there’s clarity around the tax is the products we provide are actually non-distributing funds, which means that they don’t pay out dividends. Any dividend that sits within the fund gets reinvested automatically, so that helps with thinking about tax from that standpoint.
Also, I did touch on the institutional side, just understanding the classification of this instrument because that’s key to provide clarity for local players and getting the right approvals in place so that you don’t have to do it afterwards.
And then obviously building new relationships around settlement and custody. So, that’s been quite interesting, and every market is different. We’ve also pulled in our local players as well to assist us with that process.
And then lastly, which is more my bread and butter, is around just making sure that, from a distribution and education point of view (and every market is different, as I said), we work quite closely with the exchanges to help us with the tone and the pitching and how we should position these products so that there’s greater acceptance and adoption.
So that’s the work that we do with these markets. The long and short of it is we don’t go into these markets saying, “This is how we’ve done it in SA. Therefore, you have to do it this way.” We go in, we listen, we appreciate what they are going through and we also try to figure out how we can help and make sure that we can actually improve the saving rates of the respective countries.
The Finance Ghost: Maybe a final question from my side, Duma, and obviously it’s a tricky one, but how long do you think it’ll be until we have an ETF on the JSE that says, “The Africa Basket” and it’s sitting with a whole selection of stocks based elsewhere on the continent? I think it’s a long way off, I would wager.
Duma Mxenge: It’s a long way off.
The Finance Ghost: It’s liquidity, right? It’s liquidity. It’s selection. It’s investment universe. It’s all the things, isn’t it?
Duma Mxenge: It’s a long way off. I don’t know about you, but I’ve been getting a lot of queries about, you know, “I want to invest in Dangote. How do I do that?” I was like, “We haven’t even looked at how we can actually provide a true representative of the equity market across the continent.”
As you rightfully put, liquidity is an issue. I think, at the moment, it’s a space that your actively managed Africa mandates are more suited for it. Where we think there might be an opportunity is African sovereign bonds. That is something which we think could be doable and something we can maybe provide to African investors as a whole.
The Finance Ghost: Yeah, that makes absolute sense. So, for now, if you want to invest on the continent, you actually just need to do the research, right? You need to do the work to go through the JSE-listed companies and say, “Well, who’s got big exposure into Africa?” And there are a number of them.
Duma Mxenge: Yeah.
The Finance Ghost: So, specifically, from a banking perspective and that kind of thing, if you want to take a view on Africa, that’s probably the only real way to do it from here, at the moment. But hopefully, in years to come, we may see that change, Duma, and I don’t doubt that Satrix will be at the forefront of that.
But certainly, for the time being, the focus is on taking other assets to an African investor audience. I think that’s very exciting and I really hope that it’ll be much the same journey that you’ve seen in South Africa over the next 25 years and more.
Duma Mxenge: I hope so too. I mean, we started this conversation saying that it’s a function of a partnership. What we are hoping in these respective countries is that it’s very important to also have an equity-only local strategy like we have with the Satrix Top 40.
If you go to Nigeria, for example, they’ve got what they call the NGX 30, which is basically the top 30 listed companies. And there are ETF providers who are based in Nigeria. I think they need to think about doing dual listings into South Africa because they understand their market a lot better and can provide exposure into Africa.
I think the same thing ought to take place in Kenya because when I was there, I mean, I don’t know when last you’ve been into Nairobi, or if you’ve ever been…
The Finance Ghost: I have been to Nairobi, yeah. I’ve been to Kenya once.
Duma Mxenge: The pride and joy of Kenya is Safaricom. They’ve got very good things to say about that company. As a South African, I wish I could have exposure. And again, it’s very difficult to actually access these good counters which are domiciled elsewhere on the continent. I think that is also something we want to encourage, in terms of local players thinking about doing cross-border listings.
The Finance Ghost: Yeah, absolutely. And there you’ve touched on the point, which is, if you wanted to go and invest in that, you’d have to go via Vodacom, and then you get everything else that comes with it. You get a very mature South African business. You get their exposure elsewhere on the continent.
It’s quite hard to drill down and say, “Hey, I really want East Africa.” Even just an East African ETF would be great, but even that’s really hard…
Duma Mxenge: It would be great. Yeah, yeah, that’s true [laughing].
The Finance Ghost: …So [laughing], you know, we live in a world where the index we want isn’t always available. As I’ve said many times, there isn’t even a proper retail index on the JSE. Even though we have all these retailers, there is no retail ETF tracking all the grocers, the apparel plays, and just consumer South Africa.
That ETF doesn’t exist, let alone the East Africa ETF. So, it’s not an easy thing. Liquidity can get quite thin as you move outside of the big indices.
Duma Mxenge: Yeah, no, I think we’ll get there. If you look at your global issuers, I think your broad-based indices have been covered, from an ETF perspective. What you’re starting to see now is more of the niche precision, as you said. Do you want only global banks? We can give you that.
I think at some stage we will get there in South Africa, as well as the rest of the continent, but I think we’re still way, way off. It’ll be a matter of scale. And is there increased demand? Are institutional investors and retail investors at a critical mass asking for these strategies? If there are, issuers such as ourselves are more than willing to provide ease of access to the respective markets.
So yeah, I guess we must all watch this space. We’re always monitoring and engaging even our clients to get a sense of where the interest is, where are they finding difficulty in accessing those markets. And then we can see if we can list a product that meets those needs. So, we are always listening, always taking great care in terms of making sure that we give our clients what they’re looking for.
The Finance Ghost: Fantastic. Duma, thank you so much for your time. You’re doing such exciting stuff. I imagine that you’re getting on planes a lot and that you’ve had lots of yellow fever injections and have to show your certificate at all kinds of interesting airports across the continent.
Africa is a fascinating place to do business, it really is. I’ve enjoyed my travels there.
Duma Mxenge: Yeah, it’s fine. I’m looking forward to it. I think I’ll need to also pick up new languages, especially the local languages, so I’m learning, I’m learning.
The Finance Ghost: Yeah, absolutely. It’s really cool, well done.
Duma Mxenge: Thank you!
The Finance Ghost: Duma, thanks. I look forward to seeing what’s next. We’ll definitely have you back on the show and I suspect that you’ve got lots of cool stuff in the pipeline. All the best for what’s left of 2026, and we’ll do one of these again.
Duma Mxenge: Thanks Ghost, I really appreciate it. I’m sure maybe in a year’s time I’ll be able to give you proof points in terms of how it has gone in the respective countries. But we’re quite excited and really enjoying the engagement. So, if we can make this thing work, I think I’ll be super chuffed. And the team also, it’s a big thumbs up. So yeah, there’s still a hard road ahead, but we’re excited to make it work.
The Finance Ghost: Fantastic. Ciao Duma.
Duma Mxenge: Thanks Ghost.
Satrix Investments (Pty) Ltd is an approved financial service provider in terms of the Financial Advisory and Intermediary Services Act, No 37 of 2002 (“FAIS”). The information above does not constitute financial advice in term of FAIS.
Satrix Managers (RF) (Pty) Ltd a registered and approved Manager in Collective Investment Schemes in Securities. Collective investment schemes are generally medium- to long-term investments. With Unit Trusts, Exchange Traded Funds (ETFs) and Actively-managed ETFs (AMETFs), the investor essentially owns a “proportionate share” (in proportion to the participatory interest held in the fund) of the underlying investments held by the fund. With Unit Trusts, the investor holds participatory units issued by the fund while in the case of an ETFs and AMETFs, the participatory interest, while issued by the fund, comprises a listed security traded on the stock exchange. ETFs and AMETF are registered as a Collective Investment and can be traded by any stockbroker on the stock exchange, LISP platforms and or via online trading platforms. ETFs and AMETFs may incur additional costs due to being listed on the JSE. Past performance is not necessarily a guide to future performance, and the value of investments / units may go up or down. A schedule of fees and charges, and maximum commissions are available on the Minimum Disclosure Document or upon request from the Manager. Collective investments are traded at ruling prices and can engage in borrowing and scrip lending. Should the respective portfolio engage in scrip lending, the utility percentage and related counterparties can be viewed on the ETF and AMETF Minimum Disclosure Document. The index, the applicable tracking error and the portfolio performance relative to the index can be viewed on the ETF and AMETF Minimum Disclosure Document.
Performance is based on NAV to NAV calculations with income reinvestments done on the ex-div date. Performance is calculated for the portfolio and the individual investor performance may differ as a result of initial fees, actual investment date, date of reinvestment and dividend withholding tax. Some funds may hold assets in foreign countries and could be exposed to risks such as potential constraints on liquidity and the repatriation of funds, macroeconomic, political, foreign exchange, tax risks, settlement risks and potential limitations on the availability of market information.
A feeder fund is a portfolio that invests in a single portfolio of a collective investment scheme, which levies its own charges and which could result in a higher fee structure for the feeder fund. The manager has the right to close the portfolio to new investors in order to manager it more efficiently in accordance with its mandate. A money market portfolio is not a bank deposit account. The price is targeted at a constant value. The total return to the investor is made up of interest received and any gain or loss made on any particular instrument and in most cases the return will merely have the effect of increasing or decreasing the daily yield, but that in the case of abnormal losses it can have the effect of reducing the capital value of the portfolio. Excessive withdrawals from the portfolio may place the portfolio under liquidity pressures and in such circumstances a process of ring-fencing of withdrawal instructions and managed pay-outs over time may be followed. Seven day rolling yield is calculated by taking into account the interest earned by the fund during a seven-day period minus any management fees incurred during those seven days. The yield is a current and is calculated on a daily basis. A fund of funds portfolio is a portfolio that invests in portfolios of collective investment schemes that levy their own charges, which could result in a higher fee structure for the fund of funds. AMETF are ETFs which are actively traded by a Portfolio Manager to adjust the AMETF holdings and asset allocation with the aim to outperform the benchmark. AMETF differ from ETFs which only track indices. The Manager does not provide any guarantee either with respect to the capital or the return of a portfolio. Satrix retains full legal responsibility for the co-named portfolios. For further information related to performance of a specific fund please refer to the MDD of the fund on Satrix.co.zawebsite. Full details and basis of the award are available from the Manager.
Tariffs, trade wars and toddler tantrums have more in common than you’d think. The curious history of mohair explains why, with surprising relevance for South Africa.
When my daughter was about two years old, I would take her on playdates with other children of her age. Sometimes, these playdates would be in public places, like restaurants or parks. Other times, they would be hosted at a house, either ours or the friend’s. And it was during these in-house playdates that I got to observe a ritual as old as humanity itself, played out on a much smaller (and slightly more emotionally volatile) scale.
Nine times out of 10, my daughter would bring a toy along to the playdate. Inevitably, this would lead to a moment where my daughter and the other toddler present would become completely engrossed in examining each other’s treasures. It would start with shy curiosity, then move into frank admiration, and finally devolve into territorial greed. Almost without exception, the situation would escalate to the point where both toddlers would be red-faced and screaming, wrestling their toys out of each other’s grip while shouting “MINE!”
Humans are territorial about the things they value – and apparently that instinct is present even before we learn to use the bathroom independently.
Maybe I’m strange for thinking this way (the odds are good), but this toddler exchange almost always makes me think of global trade.
Countries have been squabbling over trade for about as long as there has been trade to squabble over. In the 17th century, England and the Dutch Republic walloped each other across three naval wars, largely over who got to control the world’s shipping routes. In the 1800s, Britain went to war with China (twice) to keep the opium trade flowing in its favour. And in 1930, the US passed the Smoot-Hawley Tariff Act (which I wrote about here), slapping duties on thousands of imported goods and inviting a wave of retaliation that helped drag the world deeper into the Great Depression.
History, it turns out, loves a sequel.
Remember last year, when South Africa found itself on the receiving end of a 30% “Liberation Day” tariff from the United States? It kicked in in August, and for months, local exporters of everything from citrus to wine were left wondering whether their American customers would still be buying. Not exactly a “liberating” experience.
South Africa chose not to retaliate, which is just as well, because in February this year the US Supreme Court struck down the sweeping tariffs. Crisis averted, mostly (Washington did respond with a lower, broader levy).
Another thing we can learn about toddler tussles, if you want to take the metaphor further, is that the toy rarely stays with whoever brought it. Someone gets distracted, someone else wanders off with the prize, and by home time, ownership may well have changed hands. Global trade works in much the same way.
Take mohair, for example. The world’s most famous luxury goat fibre was born in Turkey, and for centuries, Turkey did everything in its power to keep it there. Today, its home is a lot closer to ours.
The GOAT of goats
First, let me clarify something that is needlessly confusing: mohair – the soft, fluffy, wooly stuff – comes from Angora goats. So what is angora wool then? Well, that’s the stuff that comes off Angora rabbits. And no, the rabbits and the goats are not somehow distantly related. The only thing they have in common is their fabulously fluffy hair, and the fact that they were both named after a Turkish city.
Mohair is lustrous and takes dye beautifully. It keeps you warm in winter and cool in summer, and it’s naturally elastic, crease-resistant and even flame-resistant. Like cashmere and silk, it’s considered a luxury fibre, and it’s priced accordingly.
The goats that produce the stuff originally came from central Anatolia, around the city we now call Ankara (once known as – you guessed it – Angora). Nobody knows exactly when they were first domesticated, but between the 16th and 18th centuries, mohair was the backbone of Ankara’s economy, and the fine, silky cloth woven from it dressed the Ottoman upper classes in kaftans and robes.
Europe caught wind of the goats and their fancy fleece in the mid-1500s, partly thanks to Flemish diplomat Ogier Ghiselin de Busbecq, who is credited with introducing several treasures of the Levant to Europe – the tulip, the lilac and the Angora goat among them.
Not that Turkey was making mohair’s introduction to the world very easy. The Ottomans knew exactly what they had, and expressly banned the export of both the goats and raw mohair. For centuries, if you wanted the fibre, you bought it on Turkish terms and at Turkish prices. A few enterprising foreigners managed to smuggle goats out, but the stolen herds rarely thrived in gloomy English and European climates.
So how did mohair finally make its way out of Asia? Through the front door, as it happens.
In 1838, Britain and the Ottoman Empire signed the Treaty of Balta Liman, a trade agreement that flung Ottoman markets open and let raw mohair flow out. The mills of Bradford, in Yorkshire, England, would soon be ready. Armed with new combing machines that could handle tricky fibres like mohair and alpaca, Bradford became the mohair capital of the world, and Turkey’s traditional hand-spinners simply couldn’t keep up.
But the same year that treaty was signed, something far more consequential was happening on a ship bound for the Cape.
The “oopsie” that changed it all
In 1838, 12 Angora rams and one ewe set sail for the Cape. Whether they were a gift from the Sultan or a shrewd purchase by a British colonel depends on who’s telling the story. These weren’t the first Angoras to leave Turkey; a few had made it to Spain, France and even Australia in prior years, but none had reproduced successfully on new shores.
Sounds like Turkish generosity, right? Not quite.
The rams had (reportedly) been neutered, which meant the Cape could enjoy a handful of seasons of local mohair production, but it couldn’t start a herd of its own. What the Turks didn’t know was that the singular, sneaky ewe was pregnant. Somewhere on the voyage south, she gave birth to a ram kid. If she had given birth to another ewe, the story would have ended there. Instead, the first bleating of that unlikely little ram signified the birth of South Africa’s mohair industry.
(A note for those who are concerned about goat incest – the ram was crossed with local goats, not his mother, and more Angoras were imported later).
The goats eventually found their way to the Karoo, and the Karoo turned out to be exactly what they needed. Unlike every European herd before them, they thrived, and local mohair production boomed. By the last quarter of the 19th century, South African mohair had become a serious rival to the Turkish product.
Meanwhile, back in Anatolia, the price of mohair collapsed to a fifth of its former value. In 1918, after decades of on-and-off bans, the Ottomans finally passed a law to stop breeding goats being sold abroad. One wonders why, when it appears they were a good 80 years too late. That’s what you call closing the barn door after the goat has bolted.
Today, South Africa is the world’s biggest mohair producer, supplying more than half of global production, most of it farmed in the Eastern Cape. About 90% of what we produce is exported, the bulk of it to China and Italy. Nelson Mandela Bay is now the processing capital of the mohair world, putting even Bradford’s famous mills to shame. Mohair grown in other countries is now shipped to the Eastern Cape to be processed, and then sent back out again.
Toddlers eventually learn to share. Countries, it seems, are still working on it.
The tariff drama of 2025 was a reminder that in a globalised world, nobody gets to shout “MINE!” for very long. Turkey tried for centuries – export bans, embargoes, a few reportedly neutered rams – and still the toy changed hands. South Africa, meanwhile, owes one of its most valuable exports to a goat that was never supposed to exist. It’s a useful thing to keep in mind the next time a bigger kid on the playground starts setting the rules.
About the author: Dominique Olivier
Dominique Olivier uses her love of storytelling and ideation to help brands solve problems.
Her first book, Lessons from Loss, has been published by Penguin Random House.
She is a weekly columnist in Ghost Mail and collaborates with The Finance Ghost on Ghost Mail Weekender, a Sunday publication designed to help you be more interesting.
Standard Bank, through its Stanbic Africa subsidiary, is to invest in OPay, a Nigerian mobile money company which is preparing to list its shares on the NYSE. OPay, headquartered in Singapore, operates in Nigeria, Egypt, Pakistan and Indonesia. According to Bloomberg, the size of the investment is c.$185 million, with the stake capped at 4.99% of OPay after the listing, with shares held for at least 12 months.
In an acquisition valued at £19,4 million, Bytes Technology has strengthened its capabilities across the cyber security lifecycle. The acquisition of CyberOne, which headquartered in London, was established in 2005 and is expected to continue double-digit growth reaching c. £5,2 billion by 2029. The purchase price was funded by the company’s cash resources.
ASP Isotopes, through its subsidiary Quantum Leap Energy, has signed a binding Heads of Agreement with the South African Nuclear Energy Corporation to develop, finance, construct, and operate a High-Assay Low-Enriched Uranium (HALEU) production facility at the Pelindaba site in SA.
Sanlam has announced a correction to the firm intention announcement issued on 5 October 2026. The company revised its effective shareholding in Santam to 61.9% down from the previously stated 62.7% – this after excluding Santam shares held by entities within the Sanlam Group on behalf of third parties. The all-cash offer of R505 per share to acquire the remaining minority stake remains unchanged with a further R472,47 million added to the R20,7bn transaction tag.
ADvTECH has acquired St George’s School property in Gqeberha from Curro in an undisclosed value transaction. The school will establish The Bridge School’s first Eastern Cape campus.
Unlisted Companies
Inospace, a South African owner and operator of serviced logistics parks, micro-warehouses, flexible workspaces, and self-storage solutions, has acquired a Midrand property out of business rescue. The N1-facing property, which is almost fully let, is in line with the company’s expansion drive. Inospace operates c.52 logistics and storage parks in Johannesburg and Cape Town. The purchase price was undisclosed.
B2B digital lending infrastructure company Kuunda has completed a US$5 million secondary share sale. The company builds dynamic, embedded financing solutions that create sustainable economic productivity by providing agent networks, small businesses, and consumers with access to liquidity products and services. The investment was led by E4E Africa which increased its stake as did other existing investors Accion Ventures, Portugal Gateway Fund and Seedstars Africa Ventures.
Merchantec Capital, a South African advisory firm, has been acquired by NYSE-listed Andersen, as the group expands its investment footprint into the country. The deal is one of three recent acquisition – joining corporate advisory law firm Andersen and corporate finance firm Andersen based in Italy and the Netherlands respectively. Financial details of the acquisition were not disclosed.
Fairvest proposes to issue new Fairvest B shares to raise capital via an accelerated book build. The company will aim to raise R500 million, which may be increased or decreased depending on investor appetite. In April the company undertook a capital raise of R900 million (initially R500 million), issuing 130,43 million shares at R6.90 per A Fairvest share – a 5.5% premium to the 30-day VWAP at the time. Fairvest intends to use a component of the funds to close on strategic acquisitions currently under negotiation.
Mondi has announced the results of its dividend reinvestment plans, which gave shareholders the option to received shares in lieu of a cash interim dividend. The company purchased 53,201 shares in the UK market at an average price of £8.19 per share and 384,669 shares in the South African market at an average price of R176.57 per share.
Also announcing the results of its dividend reinvestment plan was Anglo American which purchased 64,346 shares on the LSE at an average price of £40.33 per share and 258,450 shares in the South African market at an average price of R882.28 per share.
The JSE this week informed shareholders of Tongaat Hullet that the trading of the company’s shares will be terminated and the listing removed from the Main Board on 3 November 2026. The shares were suspended in July 2022 and the company subsequently entered into voluntary business rescue in October that year. The last financial information published is the unaudited consolidated financial results and operational update for the year ended 31 March 2022.
aReit Prop remains suspended on the JSE due to ongoing delays in finalising and publishing its outstanding financial statements. Annual financial statements for the financial years ended 31 December 2023 and 2024 have been prepared and are pending the audit process. The company was suspended from trading in July 2024.
This week the following companies announced the repurchase of shares:
South32’s extended repurchase programme commenced in September 2026. The company will, in total, acquire up to 4,49 billion shares with a proposed buyback end date of 10 September 2027. This week the company repurchased 1,067,063 shares for an aggregate A$5,28 million.
On 5 August 2026, Glencore announced a new US$500 million buyback programme intended to run through to February 2027. This week the company repurchased 4,960,000 shares for an aggregate £28,86 million.
Reinet Investments commenced its 7th share repurchase programme, for up to an aggregate maximum amount of €250 million subject to a maximum of 8 million ordinary shares over a period ending on 15 December 2026. The shares will not be cancelled. During the period 5 to 9 October 2026, the company repurchased 591,276 shares for an aggregate R256,3 million.
In March 2026, Quilter commenced a £100 million share buyback programme, to reduce the share capital of the company and return capital to shareholders. The third and final tranche of the programme commenced on September 8, 2026, with repurchased shares to be cancelled. During the period 5 to 7 October 2026, Quilter repurchased 3,387,115 shares on the LSE with an aggregate value of £5,94 million and 508,590 shares on the JSE valued at R19,58 million.
In June 2026, Greencoat Renewables announced its intention to commence a second tranche of the repurchase programme to return a further €25 million of capital to shareholders. The second tranche repurchase will be complete by end-December 2026. This week 704,268 shares were repurchased for an aggregate €557,633.
During the period 5 to 9 October 2026, Prosus repurchased a further 2,361,582 Prosus shares for an aggregate €83,51 million and Naspers, a further 560,739 Naspers shares for a total consideration of R396,83 million.
Ninety One plc announced an increase in the repurchase programme from £30 million to £55 million. The shares, to be purchased on the open market, will be cancelled to reduce the Company’s ordinary share capital. During the period 5 to 9 October 2026, the company repurchased a further 601,466 ordinary shares on the LSE at an average price 205 pence per share for an aggregate £1,23 million and 167,422 shares on the JSE at an average price per share of R44.90 for an aggregate R7,52 million.
British American Tobacco has again extended its share buyback to end on 23 December 2026. All shares repurchased will be cancelled. Over the period 5 to 9 October 2026, the company repurchased a further 662,841 shares at an average price of £40.44 per share for an aggregate £26,80 million.
Anheuser-Busch InBev’s US$6 billion share buy-back programme continues. The shares acquired will be kept as treasury shares to fulfil future share delivery commitments under the group’s stock ownership plans. Over the period 5 to 9 October 2026, the group repurchased 456,829 shares for €30,63 million.
Two companies issued profit warnings this week: Grand Parade Investments and Famous Brands.
One company announced, renewed or withdrew a cautionary notice: ArcelorMittal South Africa.
Fintech investor Nithio, has provided financing to Nigerian e-mobility platform MAX, extending its Series B3 funding round to US$29 million. MAX combines OEM vehicle and battery partnerships, solar-PV powered charging and swapping infrastructure, IoT-enabled fleet management, digital payments and financing into a single, vertically integrated platform.
East Africa Foods has raised US$26 million in Series B equity, led by the Private Infrastructure Development Group (PIDG) through its growth equity and project development solution InfraCo, alongside Oikocredit and FMO. The equity round completes a broader capital raise of approximately US$40 million, including investment from existing shareholders, along with debt funding from The Schmidt Family Foundation.
OPay, a Nigerian fintech, has filed for an initial public offering on the New York Stock Exchange, alongside a proposed investment of up to $200 million from Standard Bank Group. The company submitted its registration statement to the U.S. Securities and Exchange Commission on October 9, 2026, and applied to trade American depositary shares under the ticker ‘OPAY’. Its preliminary prospectus did not disclose an offering price, share count, or the confirmed listing date, leaving the amount to be raised and the final valuation undetermined.
Quick Mart PLC announced that it has received the requisite Capital Markets Authority – Kenya and Nairobi Securities Exchange PLC regulatory approvals for its Initial Public Offering and subsequent listing on the Main Investment Market Segment of the NSE. The Offer opened on 5 October 2026 and closes at 5:00 p.m. EAT on 30 October 2026. Two billion existing ordinary shares, representing 50% of Quickmart’s issued share capital, are being offered at KES 7.50 per share. The total Offer size is KES 15 billion, with a minimum application of 500 shares, equivalent to KES 3,750, and in multiples of 100 shares thereafter. The International Finance Corporation has conditionally committed to purchase up to US$15 million, approximately KES 1.94 billion, in Offer Shares. Its participation remains subject to approval by its board of directors and does not constitute an endorsement of Quick Mart or the Offer.
Shell has signed an agreement to sell its full interest in the Shell Nigeria Gas Group, which operates a domestic gas distribution business in the country, to Vaaris Energy. The companies did not disclose the monetary value of the sale. Vaaris Energy is a privately held Nigerian energy company with interests across the oil and gas value chain and an existing operational footprint in the country.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.