Fertiliser and explosive manufacturer Omnia received a firm, all cash buyout offer from Solar Industries India in a deal valuing the company at R21,83 billion. The offer of R134.50 per share represents a premium of 35.73% over the 30-day VWAP. The transaction by the Indian listed company will create a global platform to accelerate Omnia’s product offerings internationally and as such the Board intends to recommend the buyout scheme to its shareholders. The potential exit of the company from the JSE and A2X further reduces investment options available to institutional investors.
Accelerate Property Fund is to dispose of the Cedar Square shopping centre in a deal with Aristonas valued at R630 million. The purchaser will acquire the existing letting enterprise, its related income stream and available bulk but will not acquire the right to develop the bulk, this will be retained by Accelerate. The deal is classified as a category 1 transaction and as such a circular will be issued and shareholder approval sought.
In a trading update, Pepkor announced it had structured a sale and leaseback of three distribution centres unlocking R2,25 billion in capital that it will redeploy into high-growth opportunities within the group. The properties, Pep Kuils River, Pep Hammarsdale and Ackermans Hammarsdale, are housed in Badger Properties which Pepkor has anchored as a black-owned and managed property fund and in which it has retained a 35% minority interest. The property leases are 15-year triple net lease agreements which ensures operational continuity. The Competition Commission approved this transaction in June 2026.
Supermarket Income REIT has acquired a portfolio of six grocery assets for £104 million. The assets situated in the UK are across key locations bridging traditional omnichannel supermarkets, convenience stores and distribution hubs in Macclesfield, Leeds, Nottinghamshire, Birmingham, Glasgow and Avonmouth. The acquisition of the portfolio will be funded from the proceeds of the £100 million equity raise in July 2026. The average net initial yield across the assets is 6.6% with a weighted average unexpired lease term of 10 years.
The much-acclaimed R41,3 billion Vodacom deal announced in December 2025 which saw its presence in East Africa scale, has encountered a legal hurdle. Vodacom acquired a further 5% stake in Safaricom from Vodafone and a 15% shareholding from the Government of Kenya giving it an effective shareholding in Safaricom of 55%. This week the High Court of Kenya handed down an adverse judgment on a petition challenging its deal to take control of Safaricom. Vodacom is to appeal against the decision.
The disposal by Putprop of a specific portion of Summit Place located in Menlyn, Pretoria announced in November 2025 has been terminated. The deal which would have seen the property sold to Veritas 1000 for R26,5 million will not proceed as the requisite approval by the purchaser from its board of directors has not been obtained.
Unlisted Companies
Private investment firm VEA Capital Partners has announced a strategic investment in Bonisa Applied Insights (Bonisa AI), a local data science and artificial intelligence business. Bonisa AI serves clients across retail, banking, telecommunications and a range of other industries and sectors. The company also works with credit bureau data as a registered reseller, combining bureau information with alternative data sources to create additional value.
Novus has acquired an additional 10,000 shares in technology distributor Mustek on the open market at price per share of R15 (outside of the Mandatory Offer) for R152,500. The company now holds 33,14 million Mustek shares constituting 57.60% of the issued shares in Mustek. Alongside concert parties this shareholding increases to c.77.89%.
Fortress Real Estate Investments is offering shareholders the opportunity to receive the final gross cash dividend per Fortress B share as a distribution of new fully paid-up Fortress B shares in lieu of the cash dividend. Shareholders may also elect to receive the dividend as a part cash distribution and part capitalisation of shares.
OUTsurance has received approval from the South African Reserve Bank to distribute the special dividend of 87.5 cents as announced in its financials for the year ended 30 June 2026.
Visual International’s shares were suspended on the JSE in July 2026. The company has advised shareholders that its auditors require payment in full prior to commencing the audit, the costs of which are at least R1 million. Visual is in the process of raising the required funds.
This week the following companies announced the repurchase of shares:
The Pan African Resources board has approved a share buy-back programme to the value of R500 million, commencing during October 2026. The repurchased shares will be cancelled. The Company completed a share buy-back programme during the current reporting period, which resulted in the total shares of the Company decreasing by 2,003,735 at an average price of 47.8 pence (US$0.66 cents) per share.
On 5 August 2026, Glencore announced a new US$500 million buyback programme intended to run through to February 2027. This week the company repurchased 5,280,000 shares for an aggregate £31,69 million.
Reinet Investments commenced its proposed 7th share repurchase programme, for up to an aggregate maximum amount of €250 million subject to a maximum of 8 million ordinary shares over a period ending on 15 December 2026 at the latest. The shares will not be cancelled. During the period 7 to 11 September 2026, the company repurchased 545,951 shares for an aggregate R235,77 million.
In March 2026, Quilter commenced a £100 million share buyback programme, to reduce the share capital of the company and return capital to shareholders. The third and final tranche of the programme commenced on September 8, 2026, with repurchased shares to be cancelled. During the period 8 to 11 September 2026, Quilter repurchased 1,722,572 shares on the LSE with an aggregate value of £3,19 million and 269,920 shares on the JSE with an aggregate value of R10,91 million.
In June 2026, Greencoat Renewables announced its intention to commence a second tranche of the repurchase programme to return a further €25 million of capital to shareholders. The second tranche repurchase will be complete by end-December 2026. This week 687,118 shares were repurchased for an aggregate €530,903.
Ninety One plc announced an increase in the repurchase programme from £30 million to £55 million. The shares, to be purchased on the open market, will be cancelled to reduce the Company’s ordinary share capital. During the period 9 to 11 September 2026, the company repurchased a further 106,888 ordinary shares at an average price 210 pence for an aggregate £224,236.
British American Tobacco has again extended its share buyback to end on 12 October 2026. All shares repurchased will be cancelled. Over the period 7 to 11 September 2026, the company repurchased a further 506,000 shares at an average price of £40.94 per share for an aggregate £20,72 million.
Anheuser-Busch InBev’s US$6 billion share buy-back programme continues. The shares acquired will be kept as treasury shares to fulfil future share delivery commitments under the group’s stock ownership plans. Over the period 7 to 11 September 2026, the group repurchased 1,107,539 shares for €75,26 million.
During the period 7 to 11 September 2026, Prosus repurchased a further 1,771,604 Prosus shares for an aggregate €63,76 million and Naspers, a further 541,876 Naspers shares for a total consideration of R397,80 million.
Two companies issued profit warnings this week: Choppies Enterprises and York Timber.
Two companies announced, renewed or withdrew cautionary notices: Omina and Northam Platinum.
Bekia, an Egyptian startup digitising waste collection, has announced a US$765,000 seed round led by Madica, the Africa-focused investment programme affiliated with Flourish Ventures. Catalyst Fund, the pan-African climate investor to first backed Bekia in 2023, re-invested, with participation from Dakar-based Jambaar Capital. The funding will be used to grow its engineering team, take Bekia Next to market, and begin testing the model in a second African market.
Bradda Head Lithium, a North America-focused lithium development Group, has announced a conditional, definitive and binding asset purchase agreement with Zeus Resources, and its parent company, US1 Critical Minerals, pursuant to which a newly formed wholly owned subsidiary Company of Bradda Head, BHL Tanzania, will acquire from Zeus the entire rights and interests in six prospecting Uranium licences (PL 11703/2021, PL 11704/2021, PL 11705/2021, PL 11708/2021, PL 11709/2021 and PL 12354/2023), including the Mkuju Project. The total consideration under the Asset Purchase Agreement will be US$1,8 million.
Noma Services Consolidated has secured a US$650,000 loan facility from Sahel Capital, through its Social Enterprise Fund for Agriculture in Africa (SEFAA). The facility comprises $400,000 for working capital and $250,000 for capital expenditure. Noma is a Nigeria-based agribusiness specialising in the aggregation and processing of commodities including rice, maize, sorghum, and beans. Headquartered in Abuja, the company sources from a network of over 11,000 smallholder farmers (SHFs) and supplies high-quality produce to leading FMCG players.
Synapse Analytics, an Egyptian AI company that builds agentic decisioning infrastructure for regulated financial institutions putting policy control directly in the hands of credit and risk teams, announced today that it has raised US$13 million in a Series A funding round. The round was led by Partech, with additional participation from Algebra Ventures and Silicon Badia. The new capital will be used to scale the team, accelerate product development and expand international market reach.
The Kenyan government will appeal a court ruling that ordered the cancellation of the December 2025 deal in which it sold an extra 15% stake in telecoms firm Safaricom to Vodacom. Kenya’s High Court said the sale of the Safaricom stake did not adequately involve the public and was marked by concealment of material information, Kenyan television station NTV Kenya reported. It ordered the 15% stake be returned to the government.
For every entrepreneur, there comes a moment when the question changes. It’s no longer, “How do I grow this business?” Instead, it becomes, “Who is best placed to take it to the next level?”
For many founders, that moment arrives after years, sometimes decades, of building something exceptional. The business is profitable. The brand is trusted. Customers are loyal. Yet the next stage of growth requires greater scale, broader market access, additional resources or international reach that cannot easily be achieved independently.
Recognising that moment is one of the most important strategic decisions a business owner can make. That was the position in which Glenart found itself.
Founded in South Africa, Glenart had built an enviable reputation as a designer and manufacturer of premium Christmas crackers, supplying retailers both locally and internationally. Through a commitment to innovation, quality and operational excellence, the company established itself as a market leader within its niche, one that would ultimately attract the attention of one of the world’s leading celebration product businesses.
The business had reached a stage and size where the next level of growth could only come through acquisition by a strategic acquirer.
Rather than viewing such a transaction as the end of the journey, Glenart’s shareholders saw it as the beginning of a new chapter, one that would position the business for continued growth within a larger global organisation.
Their eventual partner was IG Design Group PLC, a London Stock Exchange-listed designer, manufacturer and distributor of celebration products, stationery, gifting and creative play products, with operations spanning multiple international markets. For both organisations, the transaction represented an opportunity to build on existing strengths and create a platform for long-term growth.
Navigating a complex cross-border transaction
Strategic acquisitions aren’t straightforward, and cross-border transactions introduce an additional layer of complexity. Different legal systems, regulatory environments, commercial practices and financial considerations all need to be carefully navigated while maintaining alignment between buyer and seller.
The Glenart transaction took close to two years from inception to completion, which is, in itself, a reflection of the care required to ensure that every aspect of the transaction supported the long-term interests of both parties. One of the more significant challenges emerged during negotiations around working capital.
The cyclical nature of the business, combined with its continued growth, created differing views on the appropriate working capital position. Resolving those differences required careful analysis, open communication, and a shared focus on achieving the right long-term outcome.
While negotiations naturally involve differing perspectives, the shared objective remained constant: creating a transaction that reflected the true value of the business while establishing a strong foundation for future success.
More than an acquisition
For IG Design Group, the acquisition represented more than additional manufacturing capacity. The company identified Glenart as a highly complementary business with a proven manufacturing platform, longstanding customer relationships, and a strong reputation for quality and innovation. Integrating Glenart into its global celebrations portfolio strengthens the Group’s position within a key product category, while creating opportunities for operational collaboration and continued international growth.
For Glenart, becoming part of a global organisation provides access to broader markets, increased resources, and the scale needed to continue building on decades of success.
The result is a transaction that creates value on both sides, bringing together two businesses whose capabilities complement one another and position each for future growth.
A reflection of South African business
Reflecting on the transaction, it represents something much broader than the successful completion of a single deal. It was a great reflection on the quality of businesses in South Africa.
South African businesses are robust and can be agile or measured in their response to challenges and opportunities. That resilience continues to distinguish South African businesses on the global stage. Companies that combine entrepreneurial thinking with disciplined execution are increasingly attracting interest from international strategic acquirers seeking high-quality businesses with proven capabilities and long-term growth potential.
The Glenart transaction demonstrates that world-class businesses are not defined by geography; they are defined by the quality of their people, products and operations.
Preparing for your own next chapter
While every transaction is unique, one principle remains remarkably consistent: businesses that are built for long-term excellence are the businesses that attract exceptional opportunities.
For owners considering their own future, the following simple, but powerful, advice is offered: Always run the business like you were not selling it, but were rather preparing for a listing on a stock exchange. Strong governance, disciplined financial reporting, capable management teams and operational excellence do far more than increase saleability. They create stronger, more resilient businesses, whether a transaction ultimately takes place or not.
Looking ahead
The acquisition of Glenart by IG Design Group is more than the story of a successful cross-border transaction. It is a story of recognising the right moment, preparing a business for its next phase of growth, and finding a strategic partner capable of unlocking new opportunities.
For business owners, it offers an important reminder that the best exits are rarely about stepping away. More often, they are about ensuring that the business you have spent years building is positioned to achieve even greater success in its next chapter.
As South African businesses continue to demonstrate their resilience, innovation and global competitiveness, transactions like Glenart’s serve as a powerful example of what is possible when exceptional companies are built with ambition, discipline and a long-term vision.
Anthony McCardle is a Director | Benchmark International
This article first appeared in DealMakers, SA’s quarterly M&A publication.
Changing auditors is not something most CFOs do often, but when the moment arrives, the decision can have far-reaching implications for governance, stakeholder confidence and the effectiveness of the audit process.
In this episode of Ghost Stories, The Finance Ghost is joined by Yolandie Ferreira, Head of Africa for Forvis Mazars Africa, to explore what companies should consider when appointing a new auditor and why the process is about much more than compliance.
From audit quality and industry expertise to AI, auditor independence and sustainability assurance, the discussion unpacks the factors that separate a routine audit from a truly valuable audit relationship. Whether you’re preparing for an auditor transition or simply want a better understanding of how modern auditing creates trust and accountability, this episode offers practical insights from the front lines of the profession.
In this episode:
Why companies change auditors and how CFOs should approach the transition
Common misconceptions about auditing, fraud detection and audit quality
The role of industry expertise, geographic reach and auditor relationships
How AI is changing audit processes while leaving human judgment at the centre
Why sustainability assurance is becoming increasingly important for businesses and stakeholders
Transcript:
The Finance Ghost: Welcome to this episode of the Ghost Stories podcast. I’ve got the team from Forvis Mazars back in the mix here and someone we haven’t spoken to before, which is always very exciting: Yolandie Ferreira.
She is a partner at Forvis Mazars and, more importantly, certainly for the purposes of this podcast, she is also the Head of Audit Africa.
It’s going to be a very interesting discussion because what we will be talking about on this podcast is that your auditor is actually a strategic business choice, it’s not just a compliance exercise. It’s the source of confidence in your business for your stakeholders. It’s about more than just signing off the numbers – it’s actually a trusted advisor that you are bringing into your business.
And I must say, as the team pointed out to me when we were deciding what to cover in this podcast, it’s possible to go your whole career actually, as a CFO, without really having to go through a change in auditor. It can just depend on lucky timing.
So, sometimes you come across these things. Maybe you’re not sure exactly what to think about when choosing an auditor or changing an auditor. If that sounds like something that will resonate with you, then stick with us because there’s going to be lots to learn.
Yolandie, thank you so much for joining me on the show. I’m very excited, personally, to learn from you because I’m not that jacked up on the world of audit, actually.
Yolandie Ferreira: Thank you. It’s great to be here. I hope that I can enlighten you and your listeners today to certainly understand that auditors are not all grey – and not always men, either. So, there’s a lot of value that can be added to businesses and, as you said, strategically, through the right choice of an auditor.
The Finance Ghost: Yeah, absolutely. It’s very cool to chat to you today.
Let’s talk about the decision to change auditors, because as I said, it’s not something that every CFO goes through.
I remember from my corporate finance days, you’d have the same thing on large corporate restructures, or M&A. Not every CFO has dealt with this and then suddenly they find themselves in charge of a project which is actually almost fundamental to the business and which, if you get it wrong, can actually be an existential issue. And I guess, choosing your auditor can be right up there in that regard.
So, perhaps you can kick us off by just understanding the decision to actually change auditors, what the drivers of that would be, and then what the typical timing of that decision would be, as well.
Yolandie Ferreira: Absolutely. It’s one of the most common misconceptions that companies only change auditors either when something has gone wrong or when regulation requires them to.
For a long time in South Africa, regulation didn’t actually require companies to change auditors, but that changed with the new firm rotation requirements. That’s been in place for a number of years, so most CFOs at large corporates have probably gone through one change in auditors.
But CFOs also don’t always stay in that position. As you say, it’s very possible that a CFO goes into a position, has been there for a couple of years, and then all of a sudden has to change auditors.
The thing that I see go wrong most often is that the CFO or audit committee is not focusing holistically on the process, but rather has an idea in their mind of what the auditor should be looking at right at this moment – so, either because there has been a problem in the company, or because there’s a preconceived idea that the auditor is only going to look at the past and issue an audit opinion and then move on and we’ll see them next year.
So, the timing is very important, because you want to have enough time between when you appoint a new auditor and when they need to issue their first report for the auditor to really gain a good understanding of the business. The audit report – and the auditor – are only going to be as good as their understanding of the business and the challenges that the business faces.
Anyone can probably sign off a set of financial statements and issue an audit report (well, I guess, any auditor could do that), but really adding value through that audit report is something different. That’s not something that any auditor with any standard experience would be able to provide to a company.
The Finance Ghost: Let’s start to dig into some of those concepts, because I think that’s where it’s difficult for someone who hasn’t worked closely with an audit team at that level to understand.
And certainly, for outside stakeholders, they see an audit report and they incorrectly assume (even though it generally says it), “Oh, this is audited by a big brand audit firm. Hence, it must be completely free of misstatements, fraud…you know, take your pick.” It’s like, “This is the silver bullet. We’ve caught everything.”
That’s not really how this works in practice, as we know, and there is additional value that you bring to it through sector expertise and that kind of thing. So, perhaps just deal with some of those misconceptions for us, and then also just walk us through the value of knowing a sector, for example, or maybe of being an auditor who understands listed versus unlisted companies and multinationals and those sorts of concepts.
Yolandie Ferreira: Yes, I think probably the biggest misconception out there – well, there’s two. One is that fraud can never happen if the auditor has issued an audit opinion. Well, fraudsters are quite a bit cleverer than most auditors and finance practitioners or experts, because fraud is normally all around collaboration, or doing things which are not in the ordinary course of business – quite undercover. Quite difficult for an auditor or a CFO to just pick up. Otherwise, there wouldn’t be large frauds because it would be easy to pick up.
So, I think one of the big misconceptions is that having an audit opinion from a large audit firm means that there’s nothing wrong in that company. And I think the reason for that is the very nature of audit. Auditors don’t look at every single transaction. Auditors don’t express explicit assurance that everything is right. And that’s a difficult thing to understand, particularly when something has gone wrong.
I think while everything goes right, everyone understands that. But when something’s gone wrong, then all of a sudden people will say, “Why did the auditor not see this? Why did the auditor not prevent this?”
And yet, when we talk about auditors, people will often say, “Auditors don’t bring value because they only look at the history.” But how, then, would they spot that something could go wrong potentially, if they’re only looking at the history?
So, that’s where you really need to, as CFOs and audit committees, carefully consider a couple of things when appointing new auditors.
Industry expertise is always going to be close to the top of that list, if not at the top of the list. The auditor needs to understand the unique risks and the complexities in the sector that you operate in.
It’s very different auditing a mining company to auditing a financial institution, or a retailer, or having technology and being in a business that is completely driven by technology, and bringing in an auditor that completely wants to substantively audit everything without the use of technology.
So, it’s clear, when you’re in a specialised sector, that you probably need an auditor with industry expertise. When it becomes less clear is when audit committees say, “Yes, but we’re not necessarily in a specialised sector – we manufacture.” Well, manufacturing is also a specialised sector.
But when you’re listed, that is a specialised understanding that is required of being listed versus being owner-managed versus being a large privately held business. All of these bring a different complexity that your auditor needs to understand if they’re going to add value.
All auditors audit under the same standards, so if we do our jobs properly (which we all try to do), then we will all issue the same audit report under the same standard. But where that becomes tricky is to understand the unique risks, the complexity of whether that’s the business model, the sector, the market that you operate in. And that really is something that audit committees and CFOs need to think about: whether the auditor has the relevant experience and expertise.
Quality is sometimes, you would think, easier to measure. But we only need to look at the different reports issued by the regulators across the world to understand that sometimes it’s very difficult to understand what a regulator is saying, and sometimes they come out quite clearly listing quality failures.
But how does an audit committee then apply that to their auditor? Just because a quality failure may be listed doesn’t mean that incorrect audit opinions have been issued. So, there are a lot of things which have to be taken into account, around quality and reputation, to make sure that the audit opinion carries weight because the stakeholders trust the quality standards behind it.
And for that reason, audit quality must always be a primary consideration, but it’s not always a black and white consideration. It’s something that audit committees need to get comfortable with, with the auditor, to really understand how the auditor is going to ensure quality on the opinion that they’re issuing.
Another thing I think that can be quite fundamental for a business is geographic reach. If the business is only operating in one location, it’s probably not that relevant. But many organisations these days operate in multiple jurisdictions – whether that’s within an African region, or globally; in South Africa, it may be just multiple locations within one country – and it’s always better to have an auditor who can deliver seamlessly across those different geographic locations.
If you ask my personal opinion, the people and the service model are integral to this process. Relationship really matters. Yes, the auditor must be independent, but boards should understand clearly who’s going to actually perform the work.
How accessible will the senior audit partner who’s signing off on that opinion be to the management and the audit committee, and how will the team collaborate with management and the audit committee?
It’s very difficult if management is only dealing with a manager, for instance, at an audit firm, versus when they have direct access to the audit partner who is actually going to be signing off on the opinion. So, that’s definitely something I think that any CFO or audit committee needs to make sure that they will have access to the audit partner who will be signing off on the opinion.
And then these days, you always hear from either the CFO or the audit committee, “How much AI are you going to use in the audit opinion or in performing the audit work?”
So, the profession is changing rapidly and all the firms are making use of data analytics, automation and AI to deliver more efficient audits, and often to identify insights that traditional processes may miss, purely because of the volume of data that auditors have access to and which they need to analyse.
But I think, going back to my previous point, the relationships matter. Who are you going to pick up the phone to speak to when there’s a blockage and a deadline may be in question, or when something has gone wrong and you need to understand what the impact is or how it needs to be rectified?
You can probably ask AI that, and you may get an opinion, but if you don’t have a relationship with an actual person, it’s very difficult to actually resolve those issues as they arise.
So, for me, those would be the five top things that audit committees and boards need to consider.
The Finance Ghost: Thanks. That’s such a good helicopter view of many of the factors which people need to think about, for sure. I’m so glad you brought up AI – which does not stand for ‘audit intelligence’, of course. It’s ‘artificial intelligence’, and the amount of intelligence is extremely debatable, for anyone who has been using any of these models.
Sometimes they are amazing, sometimes they are awful. The thing that always scares me is that they are a black box. It’s quite difficult to audit exactly what’s happened, ironically.
I have always wondered about where you can and can’t use AI in an effective audit process in the modern world, so I’d love to get those insights from you, and I think anyone listening to this will find that interesting as well.
Yolandie Ferreira: Absolutely. It’s undoubtedly been one of the most exciting developments in our profession. But I must tell you, I probably don’t go through any week where someone doesn’t tell me that auditors will be replaced by AI. And that is something that I do not believe.
I mean, historically, auditors have spent probably most of their time gathering, organising and analysing information, and AI and automation is helping a lot with that. It gives us insights much more quickly, and it therefore allows experienced auditors to spend most of their time focusing on actual risk assessment, applying their judgment and scepticism, and then communicating with clients.
So, we’re seeing a lot of improvements in the analysis of documents, data interrogation and (speaking to the fraud point we raised earlier) helping us with identifying unusual transactions or patterns that may warrant further attention that, when you were in the past just testing 50 items, you may never have seen those unusual patterns. So, that is all adding to the value of an audit.
But one point is extremely important, and that is that AI is not – and cannot – replace auditor judgment. Audit remains fundamentally centred around professional scepticism, ethics and governance, and human judgment.
It’s one thing to give me an answer that is technically correct, but the auditor needs to think about everything that they’ve gathered, all the information that has come to them, and really apply that professional scepticism and human judgment to make sure that we process information effectively and that we draw conclusions from there which are supported by the evidence we have gathered.
My view is that the future auditor won’t be replaced by AI at all. We will simply be enabled by AI. So, probably better auditor intelligence, rather than just AI, as such.
The Finance Ghost: Yeah, I tend to agree with that. I see it in my work, as well. It’s only as good as the prompt you give it…
Yolandie Ferreira: Exactly.
The Finance Ghost: …It’s only as good as the stuff you train it on. And whenever there’s a judgment call or you need to be able to bring together a variety of different sources and life experiences and conversations, that’s where it falls over.
Which makes sense, right? I mean, it’s just a predictive model based on the inputs that it’s seen. So, all of that makes absolute sense.
Perhaps we can now move on to some practical examples of the sort of value add that auditors do bring. Because people hear this (and you’ve raised it as well), but it’s always so good if there are some real-world examples that you’ve perhaps got at hand where – as an auditor, as an audit partner, or that you’re aware of – actual value has been added beyond just, “Hey, you are now compliant, ticking the box.”
What can you give us there to help us understand that better?
Yolandie Ferreira: I think that balance is kind of at the heart of the audit profession. Because yes, we have to be independent, and we have to maintain that independence and objectivity almost at all costs. But we also need to make sure that that professional scepticism and objectivity that we bring remains a concept that we apply to add value.
So, because we see different businesses, we see different controls and implementation of whether it is a control-system way of thinking. When we’re then working with clients, that is the value that we can bring. Our experience, the way that we’ve challenged and our objective view.
So, a good auditor should be collaborative but never compromise their independence, which is difficult. But that is why we are audit professionals.
In practice, it means asking the difficult questions which, often, management haven’t thought about because they are focused on delivering on a particular goal.
So, it is being that challenge and saying, “Have you thought about this?” Challenging those assumptions. Making sure that you do have the evidence. And we’ve seen it when sometimes – not always on the audit – but on the audit where we look at systems and controls, for instance, challenging management to really say, “This is the control you have in place, but are you actually still reaching your control objective?”
Particularly when things change so quickly in the world of technology. It may have been a perfect control process five years ago, but is it really still working?
And sometimes you see, when you hear about fraud or you’ve picked up a fraud situation at another client and you go to your client and you say, “You know this control? This is the way someone could get around that control,” or “This is a pattern that you may miss.”
The classic example (which we do still see) is that you can really, currently – specifically with technology – take away segregation of duties almost completely. And if you don’t bring controls in to compensate for the fact that one person can now do what five other people may have been involved in the process of before, then you could have an outcome where your control is actually failing because you’ve automated or you’ve brought in AI or a different system to get to a much more efficient way of doing things, but at a higher risk.
Other examples would be things like when we’re working not on an audit maybe, but to help a client review a prospectus to go into a listing or the launch of a new project. Again, it’s the experience and the objectivity of challenging the assumptions that are built into valuations, for instance. Challenging the assumptions of how perceptive a market would be to a new project.
So, I think it’s those types of things that you don’t always think about as adding value into an audit opinion, but just raising it as part of the overall audit process brings value to management, particularly where the relationship is strong enough that the mutual trust and respect is there between management and the auditors for the role that each party plays.
The Finance Ghost: Yeah, brilliant. And you’ve raised that whole working relationship with management. That’s come up a few times, actually. That is obviously something which is very important.
Of course, it’s something you also have to manage, because the whole idea is that auditors are not supposed to be too close to management – because otherwise all the familiarity issues start to come through.
So again, maybe for people outside the profession (and even for those in it, frankly) and for the CFOs out there, how do you personally practically manage independence and professional scepticism while still having that relationship with management which creates a good, efficient way to do audits?
Yolandie Ferreira: It is a balancing act. It’s not getting too close to your client, but building a close enough relationship that you can have that really honest conversation and really challenge what your client is thinking or presenting you with as evidence.
And, I guess, a mutual respect. Just building your relationship based on that mutual respect. Because we are there, both of us, to do a job. And, in the auditor’s case, you have a team below you that also, as a team, holds each other accountable, and challenges what each other is thinking, and brings the different professional scepticisms and different ways of thinking to the forefront.
But for me, the most important thing is that that relationship with your client is not a personal, we’re-friends-around-the-braai-type relationship. It is very much a professional relationship built on respect for what each of us brings to the party.
And we know that auditors need to be independent. So, as an auditor, you need to guard that line because that is what gives you that objectivity and what allows you to add value.
The Finance Ghost: I love it. You’re taking us through such a great view of auditing and how the profession actually works out there. And, last question. Another thing that’s come up in recent years, I think, is sustainability assurance. Really interesting space.
So, I generally see this play out when I’m looking from an investment perspective and I see companies raising sustainability-linked financing and that has metrics attached to it.
I can’t remember which group it was, but it doesn’t matter, there was a hospital group and they raised sustainability-linked financing, and one of the metrics was the number of people who they help from a health perspective, which blew my mind.
I’m like, “That is what you do. You are a hospital.” That has to be the best negotiated funding deal in the world. It’s like, “Our core business is to make people better. Let’s link that to our loans somehow.” So, some very clever person ran a smart negotiation with the banks there.
There’s a bigger underlying issue there, which is lots of greenwashing. ESG can sometimes be very good. It can also be very dicey. So, this all rolls up into sustainability assurance and actually just doing the right thing in that space.
Are you seeing more of these engagements coming up in practice? Is it a growth area that’s quite interesting to talk about?
Yolandie Ferreira: Absolutely. We’re seeing it more and more that all stakeholders want confidence not only in financial information, but also in non-financial information.
And the biggest challenge is that it can’t just be a warm and fuzzy story, because that’s generally where the greenwashing comes out. It has to be something which can be proven.
Whether organisations are reporting on climate risk, emissions, diversity, how many people’s lives they make better, there has to be – just like with financial information – a level of support which can be given for the information that they want to publish. Because for stakeholders to have confidence in it, you need to be able to say, “This is what I say, this is why I say this, and someone has verified that I’m not just making up nice stories.”
We’re seeing this mature rapidly globally. Just like with financial information, stakeholders want assurance that the information is reliable, consistent and, as I said, supported by evidence.
What makes it so interesting is that it’s sometimes very different to the financial reporting areas which we’re so used to having strategic implications for businesses. So, as auditors, we really need to think outside of the box.
But if you think about it, we’re used to placing reliance on experts. It’s part of what we learn to do, because we’re used to not being the expert in every single thing that we could come across from a financial information perspective. So, it’s just a different type of expert that you have to go find and really think about how you can find evidence to support what companies are wanting to report on.
So, I really believe that sustainability assurance will continue to become even more mainstream and that the broader assurance landscape will incorporate that into ultimately being part of just one level of assurance, not being spoken about even as “financial versus non-financial assurance”.
The Finance Ghost: Brilliant. Yolandie, thank you so much. You’ve given us lots to think about here. I’ll make sure that people can easily reach you via LinkedIn through some links here in the show notes. They can go and find you on the Forvis Mazars website as well.
To the CFOs out there, if you are perhaps thinking about a change in auditors or you just want to learn more about the offering at Forvis Mazars in South Africa, then please do check it out. Reach out to Yolandie.
And yeah, it’s an interesting space. It’s ever-changing. It’s very important to the fabric of our economy, so thank you for doing what you do, Yolandie, and enjoy navigating this changing world, because there’s lots going on, and I’m sure there will be plenty for us to talk about in subsequent episodes.
Yolandie Ferreira: Thank you, Ghost. And if I can leave with one takeaway, it’s that a great audit doesn’t just verify the past. It actually helps build confidence in the future.
Once upon a time, getting lost was how you found the good stuff. Then the internet learned to predict exactly where you were going – and how to redirect you.Are we in the twilight era of the digital flâneur?
When I was 14 years old, I travelled to Germany as part of my high school exchange programme. It wasn’t the brightest idea, in retrospect: I had only been studying German for a year and some change, which meant I could barely speak or understand the language. But I was young, naive and convinced that I could navigate both the foreign language and the foreign country all at once. With my parents’ blessing, I boarded the plane and took my first steps into a big, unknown world.
All in all, the trip was a success. I spent three weeks with a family in Köln, where I learned about Germans (always happy to correct your grammar), myself (surprisingly susceptible to homesickness) and the world beyond the familiar confines of my home town (more confusing, exciting, frightening and inspiring than I ever imagined).
I also learned that my German host family was way more relaxed about my general whereabouts than my parents were. On my second day in their home, they pointed me in the direction of the nearest bus stop and told me to go explore. Confused but happy to oblige, I boarded the bus alone and made my way into the centre of town, where I spent about two hours getting myself thoroughly lost.
I was too shy to ask anyone for directions (and fairly sure that I didn’t have the vocabulary or pronunciation skills anyway). So I wandered around without any particular aim, popping in and out of shops as the mood took me, until I started to get hungry. I found a restaurant on the corner of a street and went inside. There, I was given a menu covered in German that I could barely read, but I did recognise two words – “spaghetti” and “eis”, the German word for ice-cream.
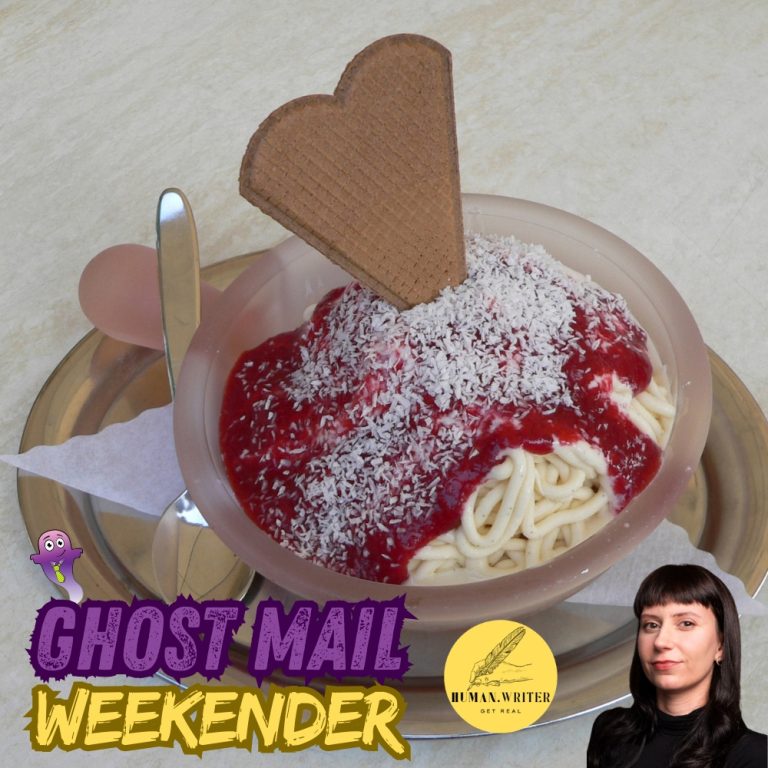
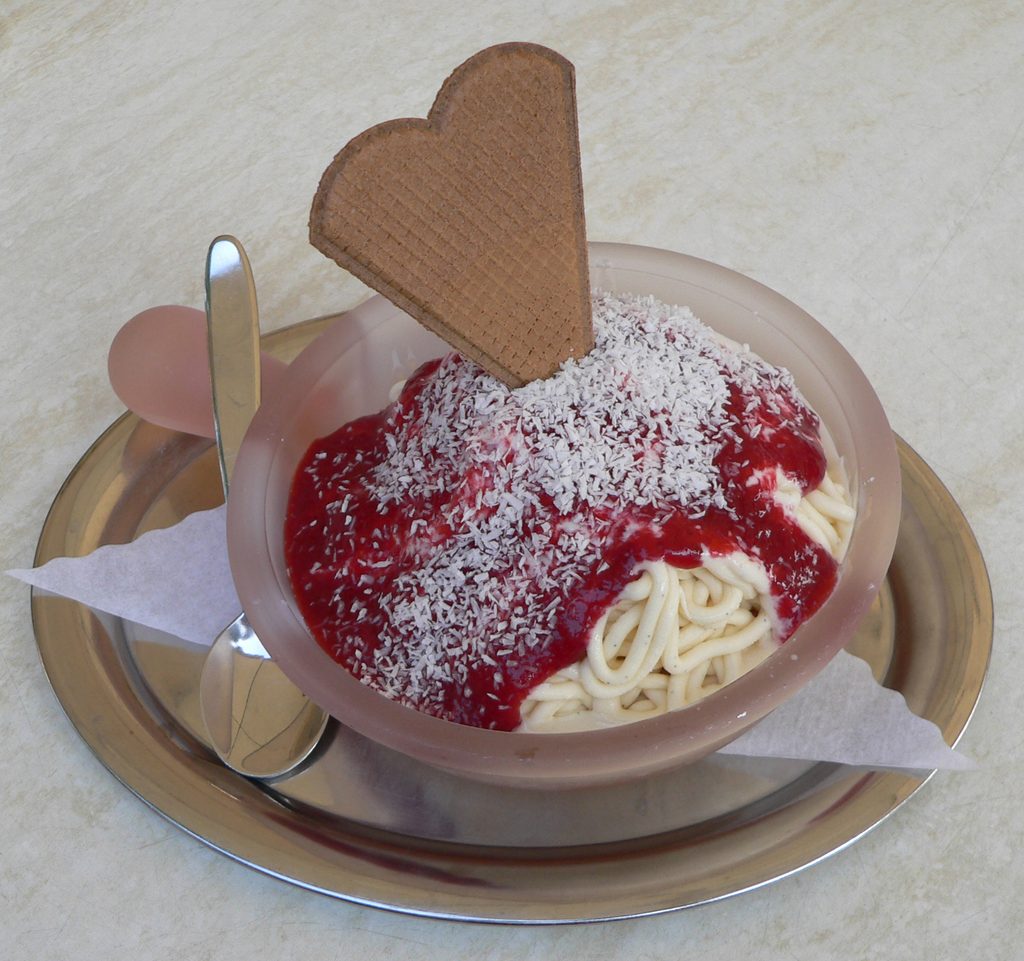
Unsure whether or not this was some sort of strange meal combo (but again too shy to ask), I ordered it. What arrived in front of me looked exactly like a plate of spaghetti covered in Neapolitan sauce, crowned with a handful of perfectly round meatballs. But the clever trick revealed itself when I tried to twirl the noodles onto my fork: it was ice-cream. The “spaghetti” was vanilla ice-cream, fed through some contraption that shaped it into realistic noodles. The red sauce was made of strawberries. And the meatballs? Chocolate truffles, of course. Spaghetti ice-cream – exactly as named.
Why am I telling you this story? Because this moment of delighted surprise, of encountering something completely novel and wonderful without really seeking it out, is something that I am finding harder and harder to achieve as the years go by. I don’t think I am alone in this experience – nor do I think that this is because of some fault or mistake on my part, or yours, if you feel the same way.
The world doesn’t have fewer new things in it. But something has made it much harder to stumble across them.
The wonder in wandering
There’s a word for what I was doing on the streets of Köln, though I didn’t learn it until I was at uni years later: I was being a flâneur. The term is French, and it belongs to the 19th century and the wide boulevards of Paris that Baron Haussmann had carved through the medieval tangle of the old city. A flâneur was a stroller, a saunterer; a person who walked the city with no destination and no purpose beyond the walking itself. Drifting and observing, the idea was to let the street deliver its surprises.
The poet Charles Baudelaire made the flâneur into something close to an artist. To stroll aimlessly, he suggested, was a way of seeing – a discipline of openness, of being available to whatever the crowd and the shopfronts and the passing faces might offer. Later, the critic Walter Benjamin spent years on an unfinished study of these Parisian arcades, the glass-roofed passages where the flâneur could wander among goods and strangers, half-shopping, half-dreaming. The point was never to arrive anywhere. The point was to remain porous to the world, to let it act on you.
It’s easy to romanticise this, and plenty of people have. But strip away the top hats and arcades and what you’re left with is something quite ordinary and quite precious: the human capacity to go looking for nothing in particular, and to be rewarded for it.
The boulevard of links
For a while, the internet was one of the great flâneur’s playgrounds. If you are old enough, you might remember what it felt like to really browse the internet, in the full, literal sense of the word. You followed a link because it looked interesting, and it took you somewhere unexpected, and that place had three more links, and an hour later you were reading about deep-sea fish or medieval siege weapons with no memory of how you’d gotten there.
Web pages were made by people, one at a time, often badly, and their badness was part of the charm. Every site was like a room someone had decorated by hand.
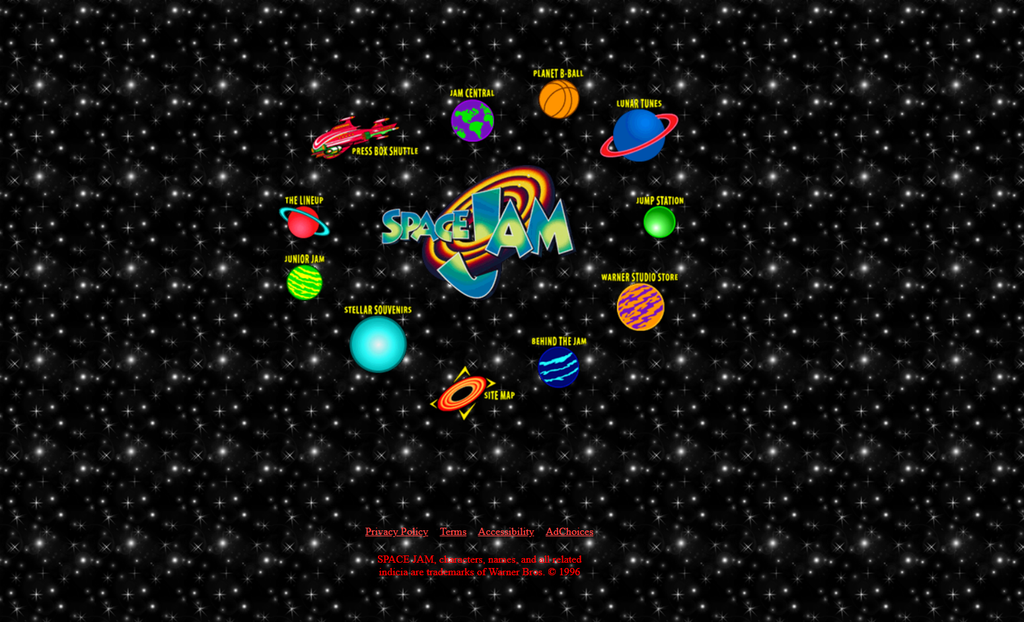
Sometimes I get a bit nostalgic for the internet that I grew up on, and when I do, I look up the Space Jam website. This is the original promotional page that Warner Bros. built for the 1996 film and then simply forgot to take down. It’s still live, decades later, exactly as it was: the corny starfield background, the planet-shaped navigation, the chunky pixelated buttons floating haphazardly in space. No banners, no ads, not a pop-up in sight.
And because we know you’re allergic to clicking anything these days, here’s a screenshot of the home page:
It is gloriously useless by modern standards. It sells you nothing efficiently. But it is a place, unmistakably, with its own weird kind of weather, and you can still wander into it and feel the particular texture of an internet that hadn’t yet decided what it was for.
That’s the internet as boulevard. What we have now is the internet as shopfront.
Today’s web is built around the destination. You arrive with a goal – a product, an answer, a booking – and the entire architecture exists to move you from intent to completion as smoothly as possible. Friction is the enemy. Every stray path has been paved over or fenced off, because a wanderer is, from a commercial point of view, a customer who hasn’t converted yet. The modern site doesn’t want you to drift. It wants you to buy, and then leave, and then come back and buy again.
The algorithm doesn’t do surprises
We rarely wander the internet anymore because we live in a world of platforms and everything apps. The feed decides. The recommendation engine decides. The algorithm watches what you linger on and hands you more of it, and more, and more, in a loop tuned with extraordinary precision to your existing tastes.
And it works. It is genuinely good at giving you what you already like. Which is exactly why it can never give you spaghetti ice-cream.
Serendipity, by definition, is the thing you weren’t looking for. It requires a gap – a moment of not-knowing, of aimlessness, of being loose in a space large enough to contain surprises. Algorithms, on the other hand, are built to close those gaps. They remove the wandering, and with the wandering they remove the possibility of the genuinely, delightfully unexpected.
I feel this most strongly when I’m on social media, where even the painters that I follow all start to look the same after a few months; I am unable to tell the work of one from another. A few weeks ago I liked a painting of a floral still-life, now every time I open my window to the world I am choked by flowers.
On Spotify, every “Recommended For You” playlist reschuffles the same five albums I have loved since varsity. I haven’t listened to a new song in months.
So what do we do about it? Beats me, honestly. Move to the platteland, delete everything, become unreachable? I’m too fond of my playlists for that (even the stale ones). International travel is the best playground for any committed flâneur, but it also costs a fortune.
But maybe I can leave a little more room for accidents – click the link that has nothing to do with anything, follow the account the algorithm would never have picked for me, take the wrong turn on purpose now and then, order the thing I can’t pronounce. Online or off, the move is the same: stop letting something else decide where I’m going before I’ve even left.
About the author: Dominique Olivier
Dominique Olivier uses her love of storytelling and ideation to help brands solve problems.
Her first book, Lessons from Loss, has been published by Penguin Random House.
She is a weekly columnist in Ghost Mail and collaborates with The Finance Ghost on Ghost Mail Weekender, a Sunday publication designed to help you be more interesting.
In a two-step transaction, Exxaro Resources will sell the Moranbah South coking coal project in Australia to Stanmore Resources for US$105 million. The asset was classified by Exxaro as non-core. In an initial step, Exxaro will exercise its pre-emptive right to acquire Anglo American’s 50% stake in Moranbah, temporarily holding a 100% stake. Immediately Exxaro will on sell the full 100% shareholding to Stanmore Resources. The transactions were triggered by Anglo selling its Australian coal portfolio to Dhilmar QLD ahead of its merger with Teck Resources.
PBT has introduced a new B-BBEE investor by way of a 30% shareholding in subsidiary PBT Innovation. The group will consolidate various operating businesses and related intra-group funding arrangements (R625m) under PBT Innovation. TheIntrepid will invest R50 million which will be locked in for eight years. PBT will use the proceeds of the BEE subscription together with available cash resources to repurchase c.13,8 million PBT shares, representing 14% of the company’s issued share capital by way of a specific repurchase for R7.50 per share, an 8.7% premium to the 30-day VWAP. This repurchase will largely offset the dilution arising from the BEE partnership subscription. A put option granted to TheIntrepid may require PBT to acquire the shares in PBT Innovation held by the BEE party in exchange for the issue of new PBT ordinary shares.
Standard Bank and Java Capital have entered into a strategic partnership designed to bring innovative capital-raising, advisory, financing and co-investment solutions together in an integrated platform. Initially the focus will be on South Africa’s real estate, infrastructure and broader real estate asset sectors.
Negotiations between Sebata and a non-related third party regarding the potential disposal of certain assets has, according to the company, been terminated.
Shareholders of Mahube Infrastructure have been cautioned that the company has entered into discussions with a consortium, of which the CEO of the company is a member, to acquire the remaining shares not already held in the listed entity.
Unlisted Companies
BetterHome Group, an established participant in the South African residential property market, is to acquire Mortgage Support Services, the parent company of Stonebridge Mortgage Solutions and a portfolio of UK mortgage, protection and technology businesses. The acquisition represents an expansion of its footprint in the UK following the investment in HLPartnership in 2024.
Over the period 19 August to 1 September 2026, Novus has acquired an additional 415,813 shares in technology distributor Mustek at an average R15.15 per share on the open market (outside of the Mandatory Offer) for R6,3 million. The company now holds 33,13 million Mustek shares constituting 57.58% of the issued shares in Mustek. Alongside concert parties this shareholding increases to c.77.87%.
AVI and OUTsurance are to pay shareholders special dividends. AVI will distribute 300c per share thanks to healthy cash flows and lower debt while OUTsurance will pay 87.5 cents per share to its shareholders on 5 October 2026.
Following the fulfilment of all the scheme conditions, the listing of Balwin Properties on the JSE and A2X will terminate on 22 September 2026.
This week the following companies announced the repurchase of shares:
During the six months to end June 2026, Libstar utilised c.R62,2 million to repurchase 13,8 million Libstar shares at an average price of R4.50 per share.
Over the period 1 July to 9 September 2026, City Lodge bought back 3,603,994 shares at an average price of R4.29 per share and cancelled 3,587,678 shares which included 150,404 treasury shares.
In March 2026, Quilter commenced a £100 million share buyback programme, to reduce the share capital of the company and return capital to shareholders. The maximum aggregate purchase price payable by the company under Tranche 3 is up to C.£30 million with the purchase of a maximum 118,097,142 shares. The third and final tranche of the programme commenced on September 8, 2026, with repurchased shares to be cancelled.
South32’s extended repurchase programme commenced in September 2026. The company will in total acquire up to 4,49 billion shares with a proposed buyback end date of 10 September 2027. This week the company repurchased 681,405 shares for an aggregate A$3,57 million.
The Old Mutual Board has approved a share buyback of up to R1 billion subject to prevailing market conditions. The buyback will proceed while the share price reflects a level that is considered accretive to shareholder value.
In June 2026, Greencoat Renewables announced its intention to commence a second tranche of the repurchase programme to return a further €25 million of capital to shareholders. The second tranche repurchase will be complete by end-December 2026. This week 591,070 shares were repurchased for an aggregate €463,266.
Ninety One plc announced an increase in the repurchase programme from £30 million to £55 million. The shares, to be purchased on the open market, will be cancelled to reduce the Company’s ordinary share capital. During the period 1 to 4 September 2026, the company repurchased a further 219,807 ordinary shares at an average price 209 pence for an aggregate £460,072.
Bytes Technology announced in May 2026 its intention to implement a new share repurchase programme to purchase the company’s shares for an aggregate value of up to £25,0 million. This week the company repurchased 308,547 shares at an average price per share of £4.14 for an aggregate £1,28 million.
British American Tobacco has again extended its share buyback to end on 12 October 2026. All shares repurchased will be cancelled. Over the period 2 to 4 September 2026, the company repurchased a further 300,000 shares at an average price of £41.20 per share for an aggregate £12,36 million.
Anheuser-Busch InBev’s US$6 billion share buy-back programme continues. The shares acquired will be kept as treasury shares to fulfil future share delivery commitments under the group’s stock ownership plans. Over the period 31 August to 4 September 2026, the group repurchased 889,223 shares for €60,93 million.
During the period 31 August to 4 September 2026, Prosus repurchased a further 1,709,990 Prosus shares for an aggregate €63,95 million and Naspers, a further 607,504 Naspers shares for a total consideration of R466,14 million.
Two companies announced, renewed or withdrew cautionary notices: Sebata and Mahube Infrastructure.
Nigeria’s Dangote Petroleum Refinery and Petrochemicals has signed offering documents with advisers and other parties involved in its initial public offering, a key milestone on its path to becoming Africa’s biggest-ever share sale. The offering will run from September 14 to October 13 and will comprise 4,1 billion ordinary shares at 525 naira each, potentially raising c.2,15 trillion naira ($1,63 billion) if fully subscribed. In the event of over-subscription, the Dangote refinery and petrochemicals plant may issue up to 30% more shares than the base offer size, subject to regulatory approval, according to the presentation.
Africa GreenCo, announced an additional US$ 11,5 million investment from its existing shareholders – the Private Infrastructure Development Group (PIDG) and Impact Fund Denmark (IFDK – formerly IFU). Africa GreenCo is a key player in Southern Africa’s renewable energy sector, with operations in Zambia, Zimbabwe, Namibia, and South Africa.
Nigerian fintech Creditchek has acquired Algosys, a Ugandan core banking software startup serving Lenders, Saccos, and MFIs in Uganda. The acquisition gives Creditchek a direct foothold in Uganda and advances its long-term strategy to build the full-stack infrastructure powering credit and lending across Africa. Following the acquisition, Algosys will operate as a subsidiary of Creditchek. Financial terms were not disclosed.
Amethis announced an investment in Zamara Holdings, an insurance broker, pension fund administrator, and provider of actuarial services headquartered in Nairobi, Kenya and operating in Africa. The size of the investment was not disclosed.
TLG Capital has closed a US$3 million senior debt facility for Drive45 Mobility, the Lagos-based mobility company providing transport solutions to businesses across Nigeria. The facility is supported by a guarantee from Cascador in collaboration with Morgan Stanley. Drive45 gives international and local businesses access to reliable transport without the cost of owning vehicles outright. The company operates more than 170 active vehicles and has recorded no payment defaults in five years of operation.
CDG Invest Growth and Mediterrania Capital Partners have signed an agreement to acquire a stake in Société Nouvelle des Conduites d’Eau (SNCE), alongside other co-investors. SNCE is a Moroccan water equipment and hydraulic projects company. The founding Laraqui family will remain SNCE’s key shareholder. SNCE operates across the water value chain, from pipe manufacturing and installation to infrastructure projects. The group works in drinking water supply and management, urban sanitation, wastewater treatment, agricultural irrigation, desalination and large-scale water transfer infrastructure. Financial terms were not disclosed.
Clean mobility company, Arc Ride has closed a US$33,3 million funding round, comprised of a $23 million Series A round, and $10 million debt. The Series A round was led by VCs Novastar Ventures and Norrsken22, with IFC, BII and Proparco ($1,5 million) joining as co-investors. The funding will support the company’s expansion in Kenya and several African countries, including South Africa, Uganda, Tanzania and Ghana.
Oxano Capital has announced an undisclosed investment in Mujuni Ventures. Mujuni is a Ugandan dairy processing and milk aggregation company headquartered in Kampala. The company operates across the dairy value chain sourcing raw milk from smallholder farmers, aggregating and quality-testing it, and processing it into its flagship brand, Too GooD Yogurt®. Sold in cups, pouches, and jerrycan packs across a range of volumes, Too GooD Yogurt reaches consumers through a network of small shops, supermarkets, schools, and institutions.
The Africa Jobs Fund has invested in Kenya-based Velocity, a labour mobility company that trains African nurses in German language and places them into jobs in German hospitals. The investment funds Velocity’s expansion into Malawi and Zambia. No financial terms were disclosed.
AfricInvest announced a minority equity investment by its AfricInvest Small Cap Fund in Spoon Consulting, a Mauritius-based AI-First Boutique Consulting and digital transformation company. The investment accelerates Spoon Consulting’s deployment of cutting edge AI architectures, expand its enterprise client footprint across Europe and Africa, and solidify its position as the high-agility alternative to legacy consultancies in the EMEA region. The size of the investment was not disclosed.
Egyptian fintech Zeal announced a US$10 million funding round by undisclosed participants, taking its total funding to $14 million. The startup currently operates with partners across the UK and Europe, the Middle East and Latin America, and has built a pipeline covering four million payment terminals globally. The new capital will be used to activate this global terminal pipeline and scale Zeal’s technology, as the company expands its payment-linked loyalty, customer identification and analytics infrastructure internationally.
Sum-of-the-parts value and the case for structural change
When the wrapper stops working. Why South African investment holding companies persistently trade below intrinsic value, and what portfolio concentration, conglomerate dynamics and structural change reveal.
A valuation puzzle commonly discussed in the South African corporate finance context – the discount to net asset value – is real, but not uniform. Apply it broadly across all listed companies and the argument becomes imprecise. The discount that is most structurally persistent sits specifically with listed investment holding companies: the gap between their market capitalization and the sum-of-the-parts (SOTP) value of their underlying portfolios. Unlike a straightforward undervaluation, this discount is not a market error; it reflects investor scepticism about the cost and efficiency of the holding company wrapper itself, although there have been exceptions (notably the PSG Group, approximately 10 years ago). That gap, and what drives it, is the subject of this article.
Why investment holding companies trade at SOTP discounts
So obvious to retail investors? An investment holding company offers investors exposure to a portfolio of assets through a single listed security. In theory, the wrapper should trade at or near the aggregate value of its constituent parts. In practice, it rarely does, and the reasons are not always clear. Generally, investors price the holding company at a discount to compensate for capital gains tax (CGT) leakage on asset disposals executed inside the vehicle, the incremental income tax drag on investment returns flowing through the structure, and corporate overhead costs at the centre – which the market views sceptically unless the holding company can clearly demonstrate that the value of its strategic oversight and capital allocation capability outweighs those costs. The risk that management’s decisions at the group level may not align with what shareholders would choose to do themselves adds a further discount. Where the portfolio consists largely of other listed entities, this cost is particularly transparent: investors can see exactly what each position is worth at any moment, making the drag of the wrapper immediately quantifiable. Listed South African investment holding companies have historically traded at SOTP discounts that have proven persistent across market cycles, as demonstrated by Remgro, Sabvest, Zeder and, before its restructuring, PSG Group. The last decade has seen this scenario play out with most investment holding companies.
The concentration effect: When one investment dominates
The holding company discount is not static; it widens materially as portfolio concentration increases. When a holding company is genuinely diversified, investors are paying for access to a portfolio across multiple sectors and risk profiles that would be difficult to replicate individually. That diversification premium partially offsets the structural drag. But when one investment grows to represent 50%, 60% or more of total SOTP, that argument collapses. Investors are no longer paying for a portfolio – they are paying a fee to own a leveraged, less-liquid proxy for a single underlying asset. The wrapper has ceased to be a benefit and has become a cost, and the market responds by widening the discount accordingly. The holding company’s traded value drifts further from intrinsic worth, not because the underlying asset has declined, but because the structural justification for the vehicle has eroded.
PSG Group and Capitec: The definitive South African case study
PSG Group’s restructuring illustrates this dynamic clearly. PSG Group was, for most of its listed life, a genuinely diversified vehicle – comprising financial services, education, food and agri, and private equity – and that diversification justified the structure. It was also the incubator of businesses like Capitec, and a listed entity with reasonable liquidity.
Over time, Capitec grew exponentially until it represented approximately 60% of PSG Group’s SOTP. The diversification rationale had dissolved: for financial services-focused investors, holding PSG Group had become functionally equivalent to an indirect, cost-encumbered stake in Capitec, trading at a persistent 30% to 40% discount despite the excellent capital allocation shown by PSG Group over the years, in terms of diversification. Other smaller investments complicated matters, and brought uncertainty regarding visibility of factors not aligned to financial services. This discount persisted, despite Jannie Mouton – the founder and Chairman who had identified and backed Capitec, PSG Financial Services (formerly PSG Konsult) and Curro long before the market appreciated their value – remaining at the helm of PSG Group. The structural drag of the wrapper proved even stronger than the credibility of one of the country’s most respected capital allocators.
The PSG Group board drew the correct conclusion and, in September 2021, PSG Group unbundled its Capitec stake directly to shareholders as a first step. A broader restructuring followed in 2022, with the remaining investments – PSG Financial Services, Curro, Zeder, KAL Group, CA&S and a portion of its interests in Stadio, among others – similarly distributed to shareholders, and the holding company delisting thereafter. The market’s response to the announcement was immediate: PSG Group’s share price closed a significant portion of its longstanding SOTP discount, confirming that the wrapper had become the obstacle rather than the vehicle. Of course, there may also have been other considerations for the unbundling.
The same dynamic played out, on a larger canvas, at Naspers and its Amsterdam-listed subsidiary, Prosus. Tencent, acquired in 2001 for $34 million, had grown to represent more than 80% of Naspers’ intrinsic value. In 2019, Naspers unbundled its international internet assets into Prosus and listed it on Euronext Amsterdam – a move intended to give the portfolio greater visibility and a broader institutional investor base. The structure, however, introduced new complexity: Prosus traded at a discount to its own SOTP, and Naspers in turn traded at a discount to its c.57% stake in Prosus. Attempts to address the situation through a cross-holding buyback mechanism – under which Prosus used Tencent sale proceeds to repurchase Naspers shares, and Naspers repurchased Prosus shares – provided partial relief, but did not resolve the structural problem.
The lesson has been clear: adding layers does not cure concentration. Genuine value realisation requires either distributing the dominant asset directly to shareholders or redeploying capital at sufficient scale to rebalance the portfolio.
For M&A advisers and capital allocators, the structural SOTP discount creates a persistent opportunity. Two observations are particularly instructive:
The signal is not the size of the discount, but its trajectory. A holding company at a stable 25% discount may be in structural equilibrium. One whose discount has expanded from 20% to 40% over 24 months, driven by the concentration of a single subsidiary, is signalling that the wrapper’s rationale has eroded – and that the market has taken notice.
Unbundling is frequently more value-accretive than a take-private. Where underlying assets arelisted and liquid, distributing them directly to shareholders avoids the need to find a buyer willingto underwrite full SOTP at a single point in time (applicable where the underlying entity meets therequirements as a standalone business). PSG Group demonstrated that the market would closethe discount organically once the wrapper is removed – no third-party capital was required.
Conclusion
The SOTP discount in South African investment holding companies is a structural feature, not a temporary inefficiency. Its drivers – such as CGT leakage, overhead cost, conglomerate discount and, above all, portfolio concentration – are well understood and consistently priced by the market. The PSG Group/Capitec case was not exceptional; it is instructive. For the right holding company – one with genuine diversification, active capital allocation and a clear shareholder value proposition – the listed structure remains a compelling platform. However, the holding company wrapper has a natural lifespan, and when the conditions that justified its creation no longer hold, structural change is the rational response. Identifying the inflection point ahead of the market remains one of the more consequential judgements in South African corporate finance.
Bhargav Desai and Sibongakonke Kheswa are Corporate Financiers | PSG Capital
Sources: Anchor Capital (2021). Update on the Naspers/Prosus Discount to NAV. anchorcapital.co.za. Moneyweb (Mar 2022). PSG to Unbundle its Investments and Delist. Moneyweb (Apr 2022). PSG Group Bids Farewell with Good Results. Perpetua Investment Managers (Aug 2025). The Investment Case for Naspers and Prosus. perpetua.co.za. PSG Group (Mar 2022). SENS Announcement: Proposed Restructuring and Delisting. JSE SENS.
This article first appeared in DealMakers, SA’s quarterly M&A publication.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.