Home Blog Page 4

African M&A Analysis H1 2026 (excluding South Africa)

0

Africa’s M&A market remained active in the first half of 2026, although dealmaking slowed compared with the same period last year. Against a backdrop of heightened geopolitical uncertainty and a more cautious global investment environment, investors have become more selective, but the underlying appetite for Africa’s longer-term growth opportunities remains evident.

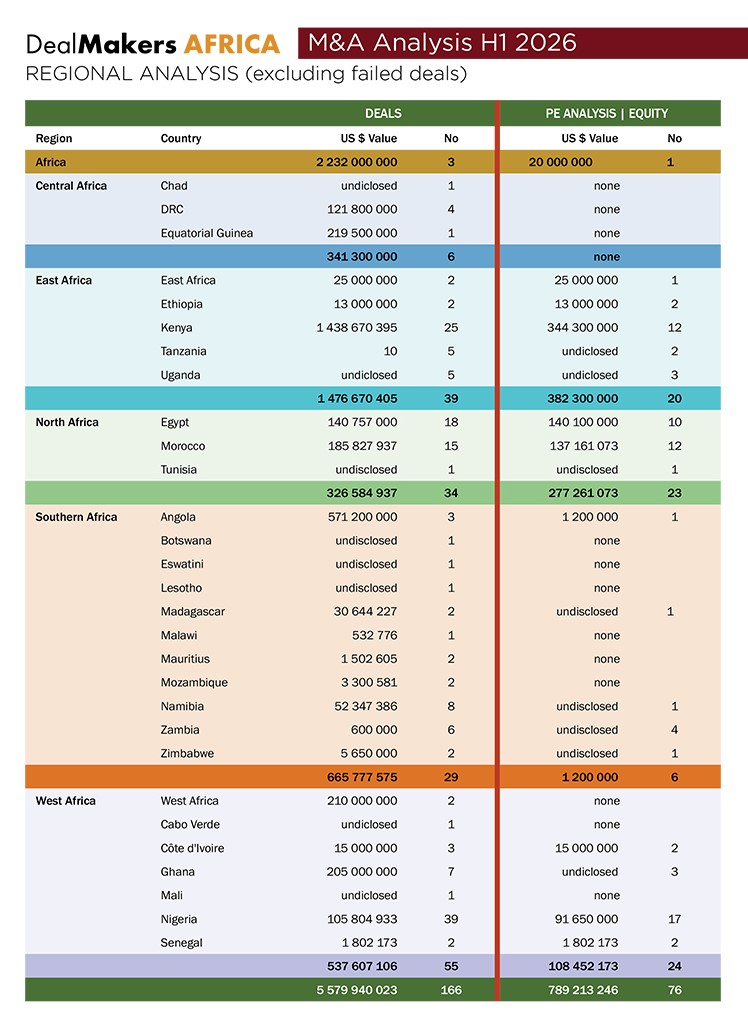
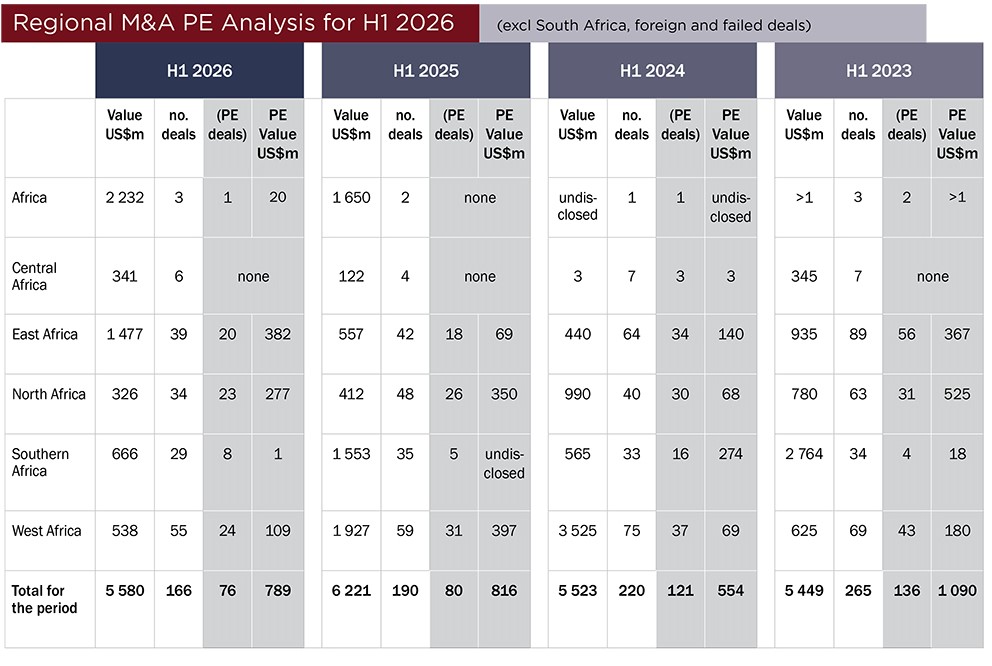
DealMakers AFRICA recorded 166 M&A deals across the continent, excluding South Africa, during H1 2026, with a combined value of US$5,58 billion. This represents a 10% year-on-year decline in deal value and a c.13% decline in deal volumes.

Source: DealMakers Online

West Africa remained the standout region, with 55 transactions accounting for one-third of all reported activity. East Africa followed with 39 deals and North Africa with 34. Nigeria led the individual country rankings with 39 transactions, followed by Kenya with 25, Egypt with 18 and Morocco with 15.

While many investors are taking a more cautious approach, Africa’s natural resources continue to draw strategic and opportunistic capital. Upstream energy and mining were notable areas of activity, with transactions in Angola, Ghana and Equatorial Guinea contributing a combined $1,21 billion. This resilience in resource-related dealmaking reflects the continued strategic importance of Africa’s commodities and energy assets, particularly as global investors position themselves for the energy transition and growing demand for critical resources.

Private equity remained an important component of Africa’s deal landscape, accounting for 76 transactions in the first half of the year. However, the longer-term trend points to a more challenging environment: private equity deal numbers have fallen from 136 transactions in 2023. The decline reflects not only greater investor caution but also the increasingly difficult exit environment facing private equity investors on the continent. For managers, deploying capital remains only one part of the equation; creating viable exit routes is becoming equally important.

Source: DealMakers Online

Africa’s entrepreneurial ecosystem is showing similar resilience. According to Africa: The Big Deal, fintech remained the leading sector for start-up funding, followed by Logistics & Transport. Agri & Food, Waste Management, and Energy & Water completed the top five. Perhaps more significant is the changing funding mix. Equity and debt are now almost evenly balanced, a notable shift from 12–18 months ago when African start-up funding was considerably more equity-driven.

Short-term caution should not obscure the structural drivers that continue to underpin Africa’s investment case. Rapid urbanisation, abundant natural resources, the energy transition and the expansion of the middle class all point to significant long-term opportunities. For investors willing to look beyond the immediate uncertainty, sectors such as ESG, fintech and value-added financial services remain areas with considerable potential.

The latest magazine can be accessed and downloaded the DealMakers AFRICA website

Who’s doing what this week in the South African M&A space?

0

Standard Bank is reportedly in early-stage negotiations to acquire a minority stake in the Nigeria-focused fintech platform OPay. This move aims to deepen the bank’s footprint in the rapidly expanding African digital payments and mobile-lending sectors. The potential investment comes as OPay prepares for its initial public offering on Wall Street, targeting a valuation of c.US$4 billion.

Balwin Properties has received shareholder approval for the PIC-backed buyout and delisting of the business. The deal announced in May this year, offered shareholders R4.35 per share implying a value for the company of R2,3 billion. The deal is expected to be implemented by 19 October with delisting from the JSE and A2X effective October 20, 2026.

Combined Motor Holdings (CMH) is to acquire various properties the company currently rents from related parties. CMH will acquire 13 properties in Gauteng and KwaZulu-Natal for R745 million – a 4.5% discount to the value attributed to the assets in April 2026.

KAP has restructured its October 2025 Southern Cape forestry transaction due to the non-fulfilment of original merger conditions. Under the newly revised, binding agreement, PG Bison Southern Cape will now be sold to Cape Pine Investment Holdings (CPIH). This restructured deal gives CPIH an 88.68% stake in MTO Forestry. CIPH will, in turn, be a wholly-owned subsidiary of Cape Forest Products – which will be 49% held by PG Bison and 51% held by Wild Peach Investments. The transaction scheduled to close on 1 October 2026.

Yellow, a fintech providing asset-backed credit for smartphones and off-grid solar products across sub-Saharan Africa, has closed a Series C funding round led by Convergence Partners and Susquehanna Sustainable Investments. The funding will be used to broaden its impact on the continent

HR tech startup Jem has raised US$8,4 million in a Series A funding round led by Quona Capital. University Technology Fund, E4E Africa, Next176 and a group of angel investors also participated in the round. The Cape Town-based firm will use the funding to expand its workforce management platform. The company was founded in 2019 as SmartWage and rebranded in 2022.

Weekly corporate finance activity by SA exchange-listed companies

0

In terms of its Dividend Reinvestment Plan (DRIP), Sirius Real Estate has on behalf of shareholders electing this option, purchased 418,910 shares in the open market of the LSE at an average price of £0.99 per share and 2,891,945 shares in the local market at an average price of R22.32 per share.

Following the results of the scrip dividend election, Acsion will issue 8,924,378 new ordinary shares in the company in lieu of an interim dividend, resulting in a capitalisation of the distributable retained profits in the company of R83,6 million. The shares were issued based on a reinvestment price of R9.37 per share.

Aimia has applied for the admission of its common shares to trading on the LSE’s AIM market. The company will maintain its current listings on the Toronto Stock Exchange and the JSE.

PSG Financial Services has received approval from the Listing Executive of the Stock Exchange of Mauritius to voluntarily withdraw the trading of its shares on the exchange. The withdrawal will take effect after the market close on 31 August 2026. The company’s ordinary shares will remain unaffected on its primary markets – the JSE and the Namibian Stock Exchange.

Sebata’s financial results for the year ended 31 March 2026 will be further delayed. The revised date had been given as 14 August, but this too was not met. An update will be provided once a reliable timetable for completion has been established.

This week the following companies announced the repurchase of shares:

In March 2026, Quilter commenced a £100 million share buyback programme, to reduce the share capital of the company and return capital to shareholders. The maximum aggregate purchase price payable by the company under Tranche 2 is up to C.£30 million. During the period 10 to 14 August 2026, Quilter repurchased 74,038 shares on the LSE with an aggregate value of £147,169 and 12,000 shares on the JSE with an aggregate value of R520,670.

In June 2026, Greencoat Renewables announced its intention to commence a second tranche of the repurchase programme to return a further €25 million of capital to shareholders. The second tranche repurchase will be complete by end-December 2026. This week 668,501 shares were repurchased for an aggregate €524,432.

Bytes Technology announced in May 2026 its intention to implement a new share repurchase programme to purchase the company’s shares for an aggregate value of up to £25,0 million. This week the company repurchased 559,112 shares at an average price per share of £4.16 for an aggregate £2,33 million.

British American Tobacco has again extended its share buyback to end on 12 October 2026. All shares repurchased will be cancelled. Over the period 10 to 14 August 2026, the company repurchased a further 610,000 shares at an average price of £42.10 per share for an aggregate £25,68 million.

Anheuser-Busch InBev’s US$6 billion share buy-back programme continues. The shares acquired will be kept as treasury shares to fulfil future share delivery commitments under the group’s stock ownership plans. Over the period 10 to 14 August 2026, the group repurchased 561,884 shares for €39,21 million.

During the period 10 to 14 August 2026, Prosus repurchased a further 2,069,018 Prosus shares for an aggregate €81,36 million and Naspers, a further 734,000 Naspers shares for a total consideration of R605,39 million.

Five companies issued profit warnings this week: Exxaro Resources, Blu Label Unlimited, RCL Foods, Cashbuild and Libstar.

Four companies announced, renewed or withdrew cautionary notices: Combined Motor Holdings, Efora Energy, Dipula Properties and Trustco.

Who’s doing what in the African M&A and debt financing space?

0

Equinor has signed an agreement with Harmattan Energy Limited, a Chevron subsidiary in Namibia, to acquire a 17.4% participating interest in Petroleum Exploration Licence 90 (PEL 90) in the Orange Basin offshore Namibia. The licence relates to Block 2813B, which is operated by Chevron. Prior to the transaction, Chevron’s subsidiary owned an interest of 52.5% in PEL 90, with the other partners in the licence being QatarEnergy (27.5%), Trago Energy (10%) and the state-owned oil company NAMCOR (10%). Financial terms were not disclosed.

A.P. Moller Capital announced that A.P. Moller Capital – Emerging Markets Infrastructure Fund II and APM Capital Morocco Fund have signed an agreement to acquire a majority stake in Globex Investissement (Globex), a Moroccan logistics company. Financial terms were not disclosed.

Panoro Energy has entered into a definitive agreement with DNO ASA to acquire the entire share capital of DNO’s wholly owned subsidiary DNO CI LLC which holds an indirect 9.09% interest in the high-quality gas producing Block CI-27 offshore Côte d’Ivoire, for US$80 million. Block CI-27 contains Côte d’Ivoire’s largest reserves of non-associated gas which is produced, together with condensate and oil, at a low unit cost of just $6/boe from four offshore fields (Foxtrot, Mahi, Manta and Marlin) tied back to two fixed platforms.

In Egypt, Exits MENA, an investment platform and advisory firm focusing on startups and SMEs, announced the signing of a multi-seven-figure transaction in partnership with ACE’s existing local management to acquire Avanz Capital Egypt (ACE), a private equity and asset management firm. Financial terms were not disclosed. ACE will be rebranded to Exits Manara as the private capital and asset management subsidiary of Exits MENA.

Terra Industries, the defense technology company that builds autonomous security systems to protect critical infrastructure across the Global South, has raised an additional US$18 million. The strategic funding closes its seed round at $52 million. Existing investors 8VC, Silent Ventures, Nova Global, Belief Capital, and SV Angel participated, alongside new investor Norleo Space Investments and angel investor Grant Gordon. Terra will use the funding to open its first international office in London, expand manufacturing capacity, accelerate deployments across the Global South, and grow its engineering, operations, and business development teams. Terra’s main operating base and flagship manufacturing facility (Pax-1) is located in Abuja, Nigeria, with an expanding major production hub (Pax-2) in Accra, Ghana.

Genser Energy Investments, an integrated energy company in West Africa, has announced the successful completion of a €456 million term and revolving credit facilities package arranged by RMB, Absa CIB and Standard Bank. The funds provide working capital to support the completion of ongoing EPC projects, strengthen the Company’s balance sheet, and provide additional financial flexibility to support its strategic priorities and continued growth.

Tusker Minerals has entered into a binding Share Sale Agreement with AuKing Mining under which AuKing will acquire 100% of the issued shares in Green Exploration Limited (GEL), a wholly owned subsidiary of Tusker’s Australian subsidiary Green Exploration (Australia). GEL is the registered holder of a portfolio of Malawian exclusive prospecting licences. Upon Completion, AuKing will acquire control of GEL and therefore the Machinga REE Project together with the Ngala Hill, Salambidwe and Karonga projects. The Agreement replaces and terminates the earlier exclusivity and proposed offer arrangement between the parties relating solely to the Machinga Project. In consideration for 100% of the issued shares in GEL, AuKing will pay A$800,000 in cash payable at Completion; Fully paid ordinary shares in AuKing with an aggregate value of $1,000,000 (issued at the same price as AuKing’s recent capital raising of $0.025 per share; $50,000 cash payable within 90 days after Completion; $1,250,000 cash payable on the date that is 12 months after Completion; plus two performance considerations valued at $1,750,000.

Save the hostilities for Christmas dinner

Hostile takeovers are as close to Hollywood-worthy action and drama as M&A gets. They usually involve a bidder seeking control over a listed company without the support of the target’s board, with a recent example being the Netflix-Paramount-Warner Bros. matter. In this article, we consider whether a similar high-stakes transaction could occur in South Africa.

South African law does not prohibit hostile takeovers and they are theoretically possible. However, there are limited viable mechanisms to effect a hostile takeover, particularly one where 100% of the shares are successfully acquired.

A scheme of arrangement (the preferred route in friendly arrangements) may only be proposed to the shareholders by the target board, effectively taking this option off the table for the hostile bidder. A hostile bidder is therefore left with one principal tool: a general offer made directly to shareholders. While this allows the hostile bidder to bypass the target board, success remains heavily dependent on the actions of the board, alongside other uncertainties.

Once a firm offer is made, the target board has a duty to adopt a passive stance and allow shareholders to consider the offer on its merits. This prevents the board from outright frustrating the offer. However, it is not a case of absolute passivity. The board retains several lawful defensive measures, including:
•encouraging opposition of the offer;
•soliciting a more welcome, competing offer;
•providing critical commentary on the merits of the offer, including price; and
•ensuring strict compliance with the letter of the law and all regulatory requirements.

These measures can stifle even the most well-planned of hostile bids.

A significant challenge faced by a hostile bidder is the misalignment between the competition law approval process and the takeover timetable.

According to the Takeover Regulations, a hostile bidder must declare an offer unconditional as to acceptances within 45 business days of the offer’s opening date. In other words, it must declare that it has received sufficient acceptances for it to proceed. However, if a general offer does not become wholly unconditional within 65 business days of the opening date, shareholders are entitled to withdraw their acceptances. In contrast, merger approvals under competition law often take far longer than this. The full process, often including frequent extensions, can take months.

This mismatch creates fundamental transaction uncertainty. Because shareholders can withdraw acceptances while awaiting competition approval, a hostile bidder cannot gauge its offer’s success before the deal goes fully unconditional.

In a hostile environment, where the target board may create additional hurdles for the competition process, including being lawfully obstructive in the provision of necessary information, delays and uncertainty persist.

Another key constraint lies in the strict confidentiality regime governing takeover activity. Before a firm intention announcement is made, negotiations between the bidder and the target board remain confidential. Even thereafter, the bidder’s ability to engage directly with shareholders is limited. While guidelines permit approach to a limited number of major shareholders under controlled conditions, broader engagement is restricted and subject to non-disclosure requirements and market abuse rules.

This creates a practical challenge, as a hostile bidder has limited opportunity to build shareholder support or publicly advocate for the transaction. Institutional investors may be reluctant to engage early, as doing so could restrict their trading in the target’s shares.

A hostile bidder may offer shares in itself as part of the purchase consideration, but such transactions may trigger additional corporate and regulatory requirements, including shareholder approvals, stock exchange disclosures and, in some cases, the preparation of a prospectus. These requirements can introduce further delays and increase execution risk, particularly where the target board limits access to target company information.

A cash offer is accordingly easier in the hostile context, but requires being able to raise sufficient capital, a challenging requirement in current economic conditions.

Often, the ultimate objective of a takeover is acquiring 100% of the shares – a difficult outcome to achieve if a scheme of arrangement is unavailable.

A bidder needs to acquire at least 90% of the voting rights (excluding those it may already hold) to initiate a “squeeze-out” of minority shareholders and acquire full ownership. Larger shareholders often delay accepting an offer without a certain prospect of success, making this threshold objectively challenging in a hostile environment. As mentioned, acceptances may also be withdrawn if the regulatory approval process drags on.

If a bidder falls short of the squeeze-out threshold, it will not achieve its full ownership goal. While it may consider acquiring a lesser number and then trying again, it is tough to achieve a squeeze-out on the second bite. The hostile bidder’s own shares in the target are excluded from the calculation of the squeeze-out threshold, making it difficult to obtain sufficient take up from the remaining shareholders to hit the 90% threshold.

If it does not acquire 100% of the shares, the bidder must deal with having minority co-shareholders, and faces practical difficulties and inconveniences in fully integrating with the target: often an unappealing prospect.

It is easy to see why hostile takeovers remain rare and seldomly successful in South Africa. The regulatory framework places significant practical constraints on unsolicited bidders; constraints which become near impossible to overcome with a target board that actively opposes the transaction at every procedural stage. Should the regulatory toil be overcome, the hostile bidder also holds no certainty in achieving the desired outcome of its bid.

While possible, hostile takeovers are far from easy. Any bidder may be better served by saving the hostilities and focusing on getting the target board on board.

Ian Hayes is Practice Head, Yaniv Kleitman, is a Director and Keagan Hyslop is an Associate | Corporate & Commercial at Cliffe Dekker Hofmeyr

This article first appeared in DealMakers, SA’s quarterly M&A publication.

Dear Private Equity: It’s complicated

Dear Private Equity,

I’ve been meaning to write this for a while. I started a few times and stopped, because I didn’t want to sound needy.

But here goes…

I like you – I always have. Everyone in my world does, really. We talk about you constantly, we dress up our best businesses hoping you’ll notice, we rehearse what we’ll say if you call. You’re clever, you’re patient, and you’ve got the kind of capital that turns a good company into a great one.

So, this isn’t a break-up letter. If anything, it’s the opposite.

After enough years walking founders across the room to you, a girl starts to notice things. The way you say one thing on the buy side and something quite different on the sell. The way you fall for her hardest when somebody else is watching. The way your patience keeps a calendar in its back pocket.

This is less a letter than a diary. The kind you write at midnight about someone you adore but cannot quite figure out. And like all good diary entries, it isn’t meant to be read by anyone. Except, well, here we are. Because lately, some of the things you tell me don’t quite add up:

1. You keep saying you don’t like a crowd
“Please,” you tell me, “don’t bring me anything that’s in process.” You want it quiet, off-market, no other suitors in the room. And I get it, nobody wants to feel like one of many.

But here’s the thing: you only really decide you want her once you can see that somebody else does too. You want her to be wanted; you just don’t want to watch it happen. You want the certainty that competitive tension creates and the price discipline it removes, both at once. And when it’s your turn to sell, you’ll run the tightest, most beautifully organised process this market has ever seen – funny, that.

2. There’s this thing about her history
“I don’t want anything that’s already been owned by one of the other funds,” you say. You want her fresh, untouched and, ideally, cheap. But we both know that one day, you’ll be the seller, standing there hoping the next fund looks at everything she’s been through – the systems you built, the governance you installed, the earnings you cleaned up – and decides she’s worth more for it, not less.

You want to buy the promise and sell the polish. It’s hard to be a discount buyer of the very thing you plan to charge a premium for.

3. Now I say this gently: you tell two different stories about the same girl
When you’re deciding whether to commit, you’re all caution. The market’s uncertain, the timing’s tricky, the multiple has to reflect the risk. Very sensible, but the moment you picture the exit, suddenly she’s remarkable, the market’s deep, everyone can see how special she is, and the multiple expands to match. Same company, same fundamentals, but two entirely different worldviews, and which one you reach for seems to depend on whether you’re the one paying or the one being paid.

4. And there’s a thing about time
You tell me you’re a long-term partner. Five years, seven years, a full business cycle. But the moment a portfolio company misses its quarterly EBITDA by a whisker, the calls get shorter, the reporting packs get thicker, and the board meeting has a very different energy. Long-term, yes, but only if the short-term keeps cooperating.

I don’t hold it against you; the LP clock is real. I’m just saying, don’t be surprised when the founder who ran the place for twenty-six years on instinct and relationships finds the quarterly cadence a little… suffocating. They built something real. They just weren’t expecting a new performance review every ninety days.

I’m not writing to catch you out.

None of this makes you wrong to want a good deal, and you’re better at it than almost anyone. I’d just love it if the game were a little more even.

And if I’m being honest with myself, which is the whole point of a diary, I keep setting you up on these introductions because the best version of you is genuinely extraordinary. The fund that comes in with real operational support. That brings the governance without the grief. That gives the founder a seat at the table, not just a cheque and a handshake. I’ve seen it. It’s rare, but I’ve seen it, and that version of you is worth writing letters for.

The people I really care about aren’t the funds, or even the advisers. They’re the founders, the families who spent thirty years building something real and asked me to introduce them to you. They deserve to feel chosen for what they are, not quietly picked up on a slow afternoon and dressed up for someone else later.

They deserve an investor who reads the room, not just the model. Someone who understands that behind the number on page four of the IM is a person who lay awake last night wondering if this was the right decision.

So this is me, still hopeful, asking the same thing I always do. Let’s talk… properly. Same table, cards up, both sides of the bread buttered fairly. I’ve long thought we’d be good together.

Yours (as ever),
An adviser who keeps setting you up on dates

Kosie Kritzinger is a Director, Corporate Advisory | Baker Tilly Greenwoods

This article first appeared in Catalyst, DealMakers’ quarterly private equity publication.

CA&S Interim Results: Broadening the platform

CA&S DELIVERS RESILIENT INTERIM RESULTS AS ACQUISITIONS DRIVE EXPANSION ACROSS SOUTHERN AND EAST AFRICA

“This was a resilient set of results in a period where consumer spending remained under pressure and currency movements added complexity, particularly in Botswana. Disciplined execution and a continued focus on operational efficiencies helped us navigate these conditions and continue to execute on behalf of clients and customers.”

Duncan Lewis – Chief Executive

FINANCIAL HIGHLIGHTS

BROADENING THE PLATFORM

As explained by Duncan Lewis, “We also made further progress broadening our platform. The acquisitions concluded during and after the period strengthen our capability in private- and confined-label distribution, e-commerce and digital offering, and position us to deepen route density and grow market share as we move into our stronger trading period.”

Through a series of acquisitions, CA&S acquired a 71.1% interest in South African distributor Sunpac, effective 1 June 2026. Sunpac is a route-to-market partner with specialist capability in the growing private- and confined-label category. CA&S also acquired a controlling stake in Pantry Club, an e-commerce business.

Subsequent to the reporting date, the group increased its existing shareholding in associates Roots Sales and Tradco Group, its East Africa business, to 64% and 55% respectively. It also acquired a minority interest in TDMC, a digital-marketing specialist.

OUTLOOK

“We expect a stronger second half than the first, in line with the group’s normal seasonal trading pattern and supported by the growing contribution of recent acquisitions made during and after the reporting period. The group intends to keep investing through the cycle, positioning the business to emerge stronger as trading conditions recover. In the near term, our priority is to integrate recent investments and realise their value, while deepening route density and growing market share,” concluded Duncan Lewis.

The group will pursue disciplined, client-driven expansion in East Africa and continue to build the digital, data and category capabilities that increasingly set its route-to-market offering apart. Active management of margin, working capital and cash, together with a strong balance sheet, gives the group the capacity to fund future growth from its own resources.

While parts of the group’s footprint remain exposed to currency movements and subdued consumer spending, the breadth of its markets and categories, its long-standing client relationships and its depth of local execution position it well to navigate the balance of the year with confidence and to continue compounding value for shareholders over the longer term.

No interim dividend has been declared for the six months ended 30 June 2026 (H1 2025: nil), in keeping with the company’s policy of declaring dividends once a year, after its financial year-end.

Read the full results here.

Note: these results have been provided by CA&S and do not include any commentary by The Finance Ghost.

BHP vs. DRDGOLD: broader into copper; deeper into gold

In this piece, I’ll be dealing with the latest results from BHP (JSE: BHG) – the largest mining company in the world with a market cap of R3.7 trillion – and DRDGOLD (JSE: DRD), a gold tailings company with a market cap of just R39 billion. Yes, that’s just over 1% the size of BHP. When we say mining giants, we mean it.

A sector of many different strategies

The mining sector is the bedrock of the South African economy. But as we know, it’s been through some tough times over the years. Famous local mining houses have responded by allocating capital to other countries in search of growth. This has had downstream implications for the country and the “deindustrialisation” trend that everyone is justifiably concerned about.

In some cases, there are mining giants that no longer have any exposure to South African operations at all. They are listed on the JSE purely to access the deep pools of mining capital that provide liquidity in the stock.

Conversely, there are also companies that are focused only on South Africa – and in some cases, only on one commodity as well! This is the riskiest way to play the mining sector, as these companies face the biggest impact from commodity price movements or regional risk changes. These things are often far beyond the control of management.

But is diversification always the answer?

Not necessarily, no. Investors can diversify their own portfolios by owning a basket of mining stocks that deliver exposure to different commodities and geographies, should they so desire.

This is the age-old debate of course: should executives diversify exposure on behalf of shareholders, or should this be left to investors to do?

One of the arguments that is rarely considered is the importance of stakeholder vs. shareholder management. It’s easy enough for shareholders to diversify, but people building their careers in an organisation can’t spend their mornings on copper and their afternoons on gold unless their employer has chosen to go this route.

Issues like attracting and retaining talent sometimes push CEOs in a direction that doesn’t always make sense to shareholders.

Mining sector capital cycles are tough, as mining companies must strike a balance between production increases and near-term returns to shareholders. It often feels like there needs to be a healthy tug-of-war between management teams and shareholders for the excess cash in the business. Usually, it’s best if both sides feel like they are winning.

With that out of the way, let’s dig into the latest numbers.

BHP: where more than half of EBITDA is now from copper

Right here on the JSE, you can invest in the largest mining group in the world without your money needing to be exchanged into a different currency. Assuming you had done so 5 years ago, you would’ve enjoyed a share price return of 65% and a total return of 134%. You must never ignore the dividend yield in these mining companies, as in this case it contributed as much as the capital gain in the share price!

The decision to be involved in BHP would require you to be bullish on copper. The company calls this the “engine that is driving BHP’s growth”, contributing more than half of underlying EBITDA for the first time. It also generated enough free cash flow in the latest period to be self-funding.

The 48% increase in underlying EBITDA from copper was driven by a 35% jump in the average realised price, driven by themes like electrification and data centres. Although expected global demand growth of 2.8% in 2026 is below original expectations due to the global disruption of the Iran conflict, it’s still ahead of the 2.1% growth in 2025. When demand is good, prices tend to go up.

And thanks to that spectacular jump in prices, BHP can mask a 3% decline in copper production. It’s certainly a lot sexier to point to a metric like Return on Capital Employed (ROCE) of 26%, up from 17%.

These returns don’t emerge from the ground on their own. It takes a lot of capital to diversify like this. Copper capex was $4.7 billion in FY26, up from $4.5 billion in FY25 and expected to grow to $5.4 billion in FY27. The capex plans are designed to deliver copper production CAGR of 3% to 4% between FY27 and FY35.

What about the rest of BHP?

BHP’s ongoing ability to grow in copper is made possible by the excellent underlying iron ore business. This has been the anchor of the group, with BHP focused on markets that are very far away from Transnet and all the South African infrastructure headaches faced by the likes of Kumba Iron Ore (JSE: KIO).

They have to beat off some terrifying wildlife on the other side of the pond, but Western Australia Iron Ore (WAIO) is the lowest cost major iron ore producer in the world. This operation is core to BHP’s business, with record production and shipments achieved in FY26.

Admittedly, the new record was achieved with growth of just 1% in production in FY26. Average realised prices climbed 3%, driven by Chinese demand and higher energy costs due to the Middle East conflict. With cost pressures in the mining process, underlying EBITDA was up by just 1%.

ROCE slipped from 43% to 41%, although you’ll notice that this is still miles above copper. It helps to have infrastructure that has been in place for decades.

Still, the cash cow that is iron ore is a cash cow does come with a capex bill. They allocated $3.2 billion in capex in FY26, up from $2.7 billion in FY25 and expected to dip to $3.1 billion in FY27.

And here are two interesting facts about emerging markets from the iron ore section for you. The first is that BHP expects China’s real steel production to plateau for the rest of the decade, with scrap playing an increasingly important role. The second is that India is expected to transition from a net exporter of iron ore to a net importer, as domestic iron ore supply is lagging behind steel capacity growth.

Let’s not talk about South African demand for steel. It’s too depressing.

Shhh… quick, over here… BHP is also still producing coal

BHP downplays coal in the earnings narrative, perhaps because they are scared of getting shouted at by environmentalists who believe that the world should run on sunshine, wind and vibes, even though it can’t.

I’m a big supporter of renewable energy, but I also live in the real world. I recognise that since man invented fire, we’ve stood a better chance of surviving out there. Coal is good at making fires and generating energy, whereas Mother Nature tends to have a mind of her own. In the same way that BHP has diversified its operations, we should have diversified sources of energy.

There’s also another good reason why coal gets minimal attention: it’s only 3% of group EBITDA.

In the latest period, steelmaking coal saw production increase by 3% and average prices by 8%. Energy coal production was up 9%, but average prices fell by 3%. Underlying EBITDA was up 45% in this business, with an EBITDA margin of 15%.

That margin is much lower than you’ll find in copper or iron ore, as evidenced by the group margin sitting 6 percentage points higher at 59% – the highest level in four years! It’s copper growth that took them there, with coal having a negative mix effect on margin.

Coal capex was just $0.4 billion, down from $0.5 billion in FY25 and also lower than the expected $0.4 billion in FY27.

A final note on BHP

With net operating cash flow up by 17% and capex increasing by only 5%, BHP just unlocked free cash flow growth of 83%. It’s a fantastic set of numbers.

The focus on copper and iron ore as the high margin plays is working. And to make sure that the BHP of tomorrow also has a good story to tell, they are allocating capital to new areas like the Jansen Potash project (capex of $1.8 billion in FY26).

BHP has the balance sheet to take these risks, with net debt of $8.7 billion sitting below the target range of between $10 billion and $20 billion. The net debt to underlying EBITDA ratio is just 0.3x.

DRDGOLD: capex focused on existing operations

As you’ve hopefully realised, BHP’s capex drive is about broadening their group. At DRDGOLD, they are focused on making the most of their existing operations, although there’s a one-liner right at the end of the earnings presentation that needs to be considered carefully. I’ll cover that right at the end.

If you have a look at the presentations section of the DRDGOLD website, you’ll find one from mid-July called Vision 2028 Capital Projects Update. This very official-sounding deck was designed for one thing and one thing only: to explain to shareholders where their capital is being invested.

It was a solid presentation, with an honest appraisal of the difficult situation that the company found itself in during 2023. In their words:

“Ergo was running out of tailings capacity and margin. FWGR was running out of room to grow. Vision 2028 fixes both.”

There we have it. Throw money at your problems and they tend to go away. It works better in mining that it does in retail, that much I can tell you.

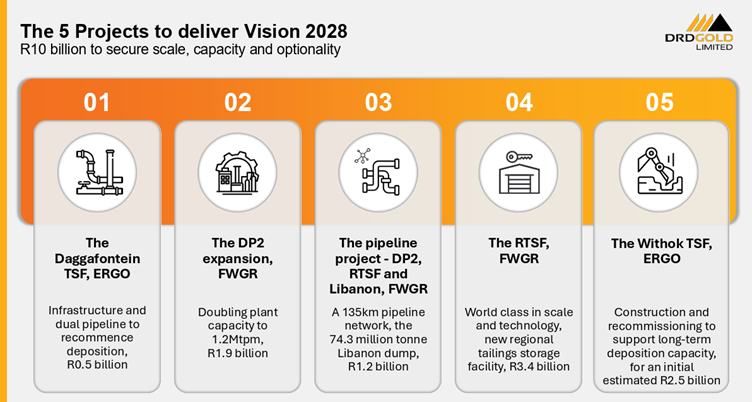
Practically, this means that a number of projects at DRDGOLD are in progress. Here’s how R10 billion is being allocated:

In the latest results, there’s an update to the numbers. The Withok TSF at Ergo has been increased to a R3 billion spend. The other numbers are all the same. What’s a casual R500 million between friends?

Also, though it may be called Vision 2028, that particular project is only expected to be completed in 2029. Perhaps Vision 2029 didn’t sound quite as appealing.

Jokes aside, as DRDGOLD doesn’t come close to the scale of the mining giants out there, they have to be more cautious with how they allocate their capital.

What do the latest numbers look like?

The year ended June 2026 is highlighted by DRDGOLD as being the 19th consecutive year of dividends. Not dividends growth, mind you – simply the existence of dividends. The financial media loves juicy taglines like these, so DRDGOLD is only too happy to provide them.

I think the far more important point is that revenue has jumped by 42%. That hardly sounds like a business that was at a production crossroads, but a deeper look quickly reveals that the gold price increase of 40% over the past year is the driver here.

Therein lies the real story: tonnage throughput actually fell by 2%, so they processed less ore than in the prior year. Thanks to an increase of 2% in the average yield (the amount of gold extracted from the ore), DRDGOLD increased production by just 0.2%. The company has been reliant on the gold price behaving itself, a factor that is completely outside of their control.

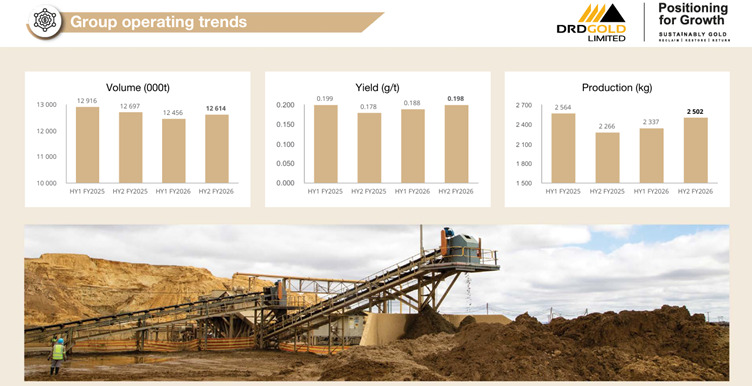
This slide does a good job of showing you why they need to put heavy capex into growing their volumes and subsequent gold production:

As you can see, volumes have been a sideways story, with production dependent on volatile yields.

The difficulties in extracting the gold has led to cash operating costs per kilogram increased by 7%. This shows you how quickly things could’ve gone wrong in the absence of an increase in the gold price. But this also means that in a year where the gold price does really well, DRDGOLD banks the benefit of high operating leverage (the prevalence of fixed costs in the cost structure).

That’s exactly what happened recently, with operating margin jumping from 47.7% in H2’25 to 61.2% in H2’26.

Here’s the real kicker: H2’26 HEPS of 268.7 cents is higher than total FY25 HEPS of 260.8 cents! In six months, they made more than the entire prior year. Life is good when your only commodity in your mining company is experiencing a generational upswing.

DRDGOLD’s outlook: more production, but watch those costs

Guidance for FY27 is for production of between 160,000oz and 170,000oz, which is odd when the rest of the report focuses on kilograms.

This has forced me to learn that one kg of gold is 32.1507 troy ounces. The converted guidance is production of approximately 4,976kg – 5,288kg vs. production of 4,839kg in FY26. That’s a 6% increase at the midpoint.

Before you get too excited at the prospect of all this additional gold, the cash operating cost is expected to climb to R1,099,000/kg. That’s a 13.6% jump from FY26, suggesting that inflationary pressures are coming through thick and fast.

There’s also planned capital investment of R3 billion in FY27, down from R3.5 billion in FY26. Although shareholders will be happy to see a dip in capex, they will also be wary of overruns.

And what about that throwaway comment I referenced earlier? That one-liner in the preso? Well, on the last slide, the final bullet of the outlook section is a note about DRDGOLD “exploring growth opportunities beyond South Africa.”

Hmmm.

HEPS may have just increased by 89% at DRDGOLD, but the company famously has a conservative balance sheet that doesn’t use debt. I hope that they won’t bet the farm on opportunities beyond our borders. South Africa has many challenges, but investors will be nervous of any foreign capital allocation during a period of heightened capex in the existing operations.

The last company that bit off way more than they could chew is Gemfields (JSE: GML). We all know how that ended, with the share price down 83% over 3 years.

Taking risk can be a good thing, but too much of it can kill you.
Absa vs. Standard Bank: African ambitions, South African money machines

In this deep dive, I look at the recent results of Absa (JSE: ABG) and Standard Bank (JSE: SBK). There’s much to learn from these financial services giants, but there’s one clear theme that came through for me: while Africa may tell a great story in a slide deck, the South African businesses are still doing the heavy lifting.

Absa’s results presentation uses a map of Africa on the cover page. Standard Bank’s tagline in the report is “Africa is our home, we drive her growth”. Yet both groups generated more earnings in South Africa than on the rest of the continent combined!

Africa is an important source of growth and diversification. It can also be a highly lucrative place to do business, evidenced by Absa’s net interest margin of 735 basis points in Africa Regions vs. 378 basis points in South Africa.

Just don’t underestimate South Africa as the anchor market for these groups. Local is firmly still lekker.

Standard Bank is much bigger than Absa – and generates higher ROE

Absa operates across 17 countries on the continent and has 13.4 million customers. That’s impressive, but Standard Bank is the largest financial services group in Africa, operating across 21 countries and with 20 million active customers.

Scale matters in this game, as it drives efficiency and diversifies risk. Case in point: Standard Bank has now achieved 10 consecutive six-month periods of positive jaws, while Absa is guiding for negative jaws for the full year.

This scale difference can be observed in Return on Equity (ROE), a key valuation metric for a bank. Absa’s ROE improved from 14.8% to 15.0% in its interim period. This 20 basis points improvement looks solid until you compare it to Standard Bank’s increase from 19.1% to 19.8%.

These are structurally different ROEs, which helps explain why Absa and Standard Bank also trade at such different valuations.

Understanding the SA vs. Africa story

Absa’s stated ambition is “to be a leading pan-African bank”, so they think far more broadly than the original acronym would imply. In case you’re wondering, Absa dropped the underlying Amalgamated Banks of South Africa all the way back in 1997. That’s your trivia out of the way for the week!

The problem is that the Africa Regions segment at Absa didn’t grow in the interim period. Revenue fell by 3% and headline earnings was down by a nasty 10%. Conversely, South Africa grew revenue by 8% and headline earnings by 17%.

The South African contribution to Absa’s group headline earnings increased from 66.0% to 71.7%. Kenya and Ghana contributed a combined 11.5%, with the remaining markets contributing 16.8%.

Over at Standard Bank, SBSA (the local business) grew headline earnings by 14%, roughly double the 7% achieved by the Africa Regions. SBSA contributed 51% of group headline earnings vs. 40% in Africa and the remaining 9% in the offshore and ICBCS operations.

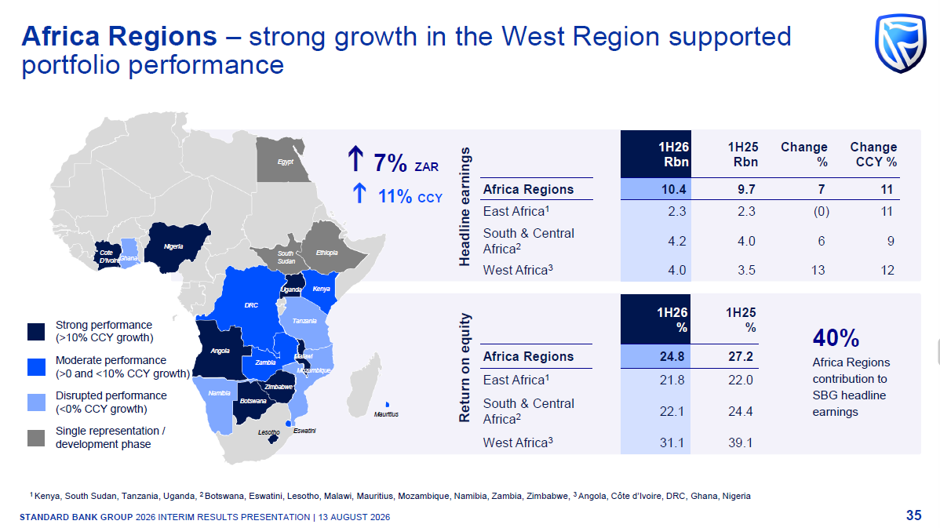
Kudos to Standard Bank for this lovely slide showing the pockets of growth in the latest period in Africa:

Unpacking the credit performance

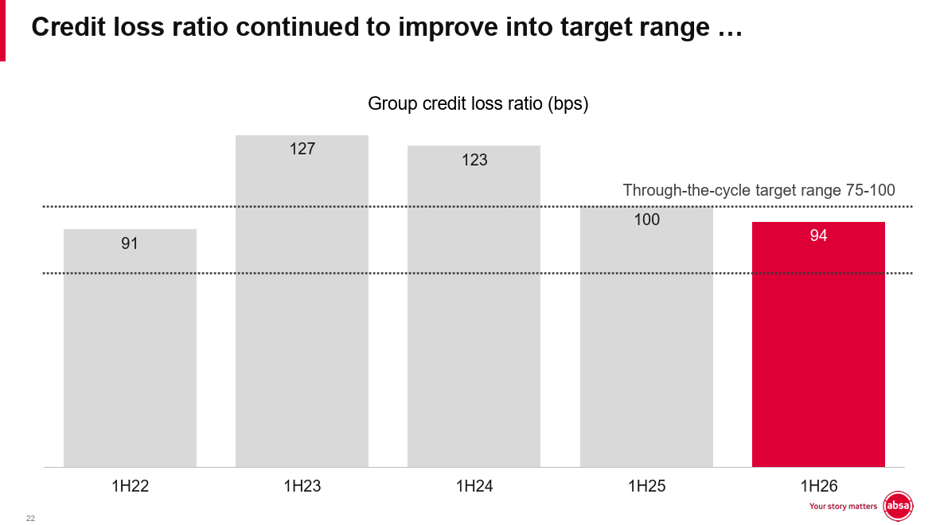
Absa’s revenue increased by just 4% for the period, yet HEPS was up by 8%. This is thanks to a 1% decrease in impairments, with this slide doing a great job of showing how a credit loss ratio tends to go through cycles, with the through-the-cycle target range held steady (thereby doing what it says on the tin):

As you can see, the latest period saw an improvement in this ratio from 100 basis points to 94 basis points.

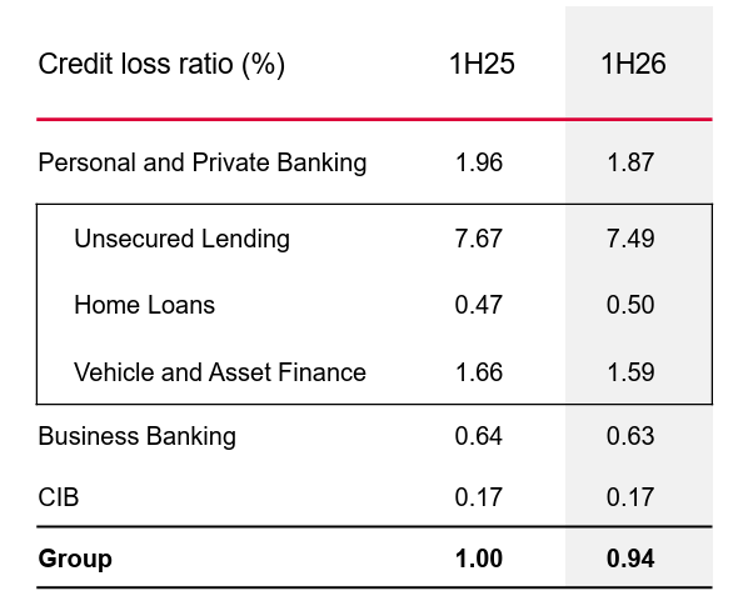
That may come as a surprise, especially given the macroeconomic backdrop to these numbers. Something else that you may not have seen before is the enormous difference in credit losses between unsecured lending (like personal loans) and secured lending (vehicle finance and home loans). If you’ve ever wondered why personal loans have to be priced so high, here’s your answer:

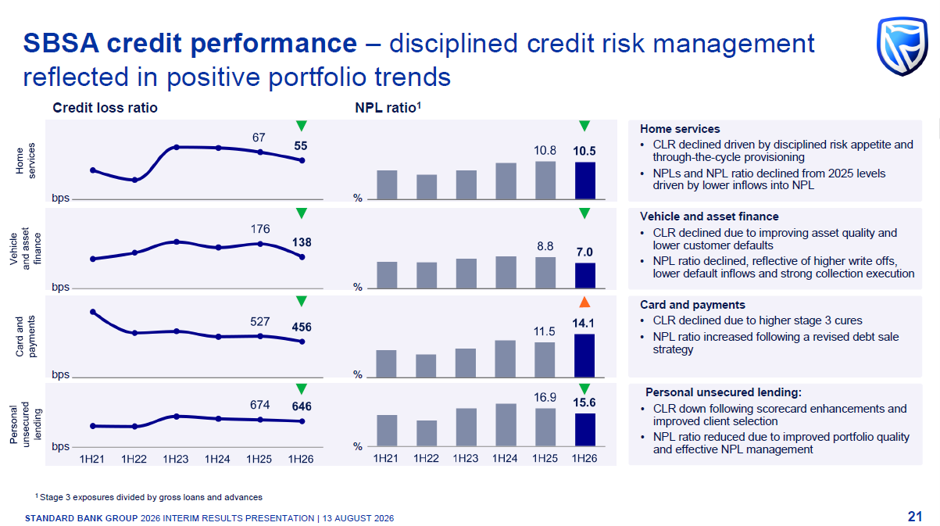
Over at Standard Bank, group headline earnings grew by 10% despite total income only growing by 5%. In this case, the improvement in impairments was even more extreme: it fell by 12%, giving banking earnings quite the boost.

This was driven by a decrease in the credit loss ratio across the four major lending businesses in the personal banking side of SBSA, driving an improvement in the group credit loss ratio from 93 basis points to 73 basis points:

Both banks are telling a better impairments story than before, but Standard Bank has enjoyed the biggest positive move. The credit loss ratio at Standard Bank is also considerably lower than at Absa.

Business banking: a critical market

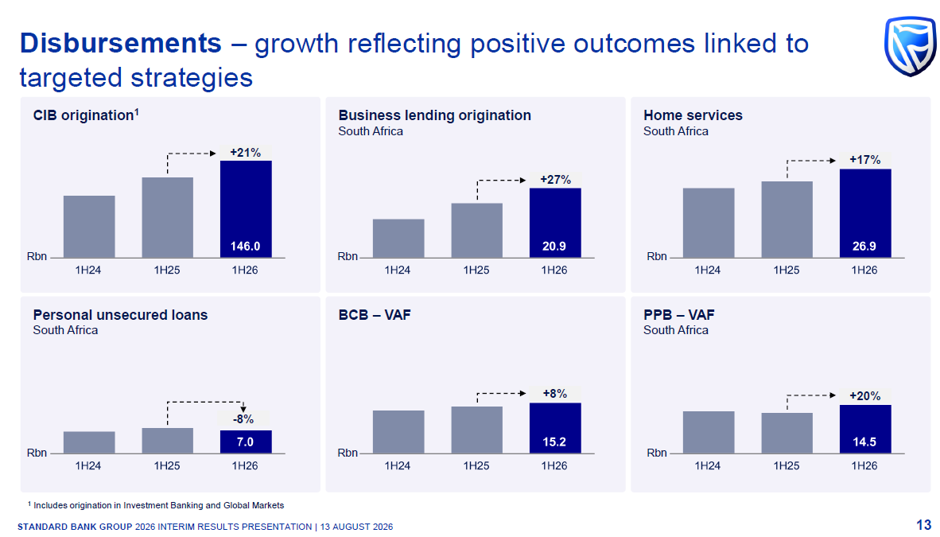
There are many different products offered by these banks. They also focus on different things at different times. At Standard Bank for example, there’s been a clear tilt in disbursements away from unsecured loans and towards corporate and business banking activities, as well as home and vehicle asset finance:

But the thing that surprised me most in this deep dive was just how lucrative the business banking operations are at both banks.

At Absa, this segment offers the best ROE in the group (up from 23.1% to 24.6%). It grew earnings by 5%, well ahead of the 1% growth in Corporate and Investment Banking for example.

The Business and Commercial Banking segment at Standard Bank is even stronger, boasting a 36.3% ROE. It’s under pressure though, with ROE down from 37.5% in the prior year due to a decline in headline earnings of 2%.

It’s little wonder that Capitec (JSE: CPI) is aggressively expanding into this space! Any market share lost by the legacy banks to Capitec will hurt their ROE.

Insurance as a driver of returns

The bancassurance model is designed to drive higher ROE through generating insurance profits from banking clients. Standard Bank seems to be doing a much better job of it at the moment.

Absa suffered a 2% decline in headline earnings in the insurance segment of the personal banking business. It barely gets a mention in the earnings presentation.

Conversely, insurance and asset management is a distinct segment at Standard Bank. It’s not a perfect comparison to the Absa numbers, but that’s also the whole point – Standard Bank is giving it far more focus. The blue bank enjoyed headline earnings growth of 15% in this segment!

This was helped along by the short-term underwriting margin coming in at an excellent 17% vs. the target of 10%. Also don’t underestimate the asset management business at Standard Bank, with assets under management and administration up 23% in Africa Regions and 13% in South Africa.

ROE in this segment at Standard Bank was 19.7%, ahead of the personal banking business at 19.2%. It’s also a lot higher than Absa’s group ROE, so this is an area where Absa could look to compete more effectively.

Watch those jaws

The concept of jaws in banking is interesting. It measures the difference in growth rate between income and expenses. Simply put, a negative jaws scenario arises where expense growth is outpacing income growth, leading to a decline in margins.

Absa has guided only low- to mid-single digit revenue growth for the full year. In an inflationary environment, that puts the group at risk of “slightly negative jaws” according to the guidance. Staff costs (up 6%) will need to be closely watched here, as this line contributed 58% of total costs in the interim period. Technology also needs to be carefully managed, with growth of 6%.

Spare a thought for those earning advertising revenue from Absa. Marketing costs fell by 9% to just over R1 billion. Absa can’t just rely on an improving credit loss ratio to keep boosting earnings, so perhaps they need to invest more aggressively in growing the brand and the business?

At Standard Bank, staff costs were 59% of total costs and grew 6% – a remarkably similar performance to Absa. Software, cloud and tech spend increased by 6%, so that’s also well in line with what we are seeing at Absa. The difference is in revenue, with Standard Bank maintaining guidance of mid- to high-single digit revenue growth.

That’s enough for positive jaws for the full year and for ROE to grow vs. 2025 (based on guidance).

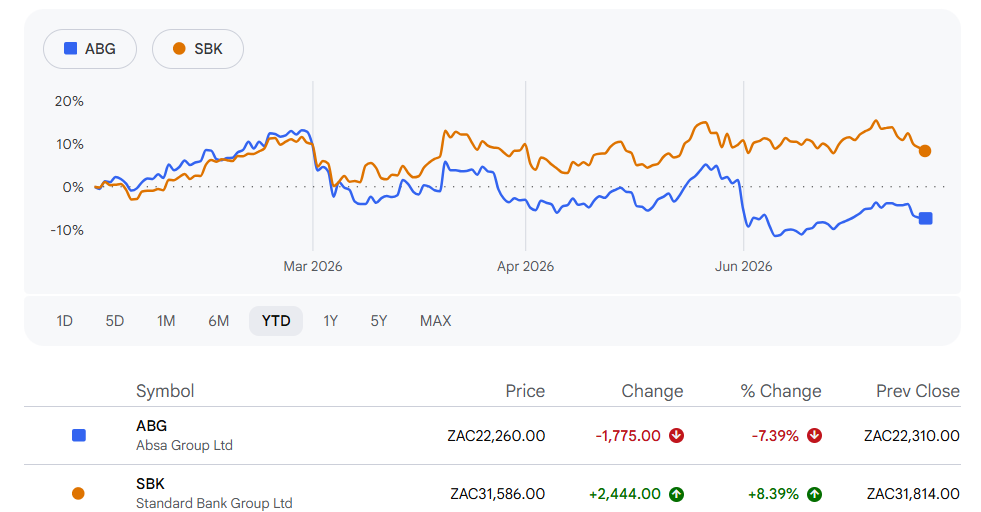
It’s also enough for Standard Bank to be outperforming Absa on a year-to-date basis, with the market choosing to back the scale player in Africa:

They may both be legacy banks, but there are many interesting differences once you start to unpack them.

Ghost Bites (ASP Isotopes | RCL Foods | SPAR | Thungela)

In this edition of Ghost Bites:

  • ASP Isotopes’ quarterly results show how early the company is on its journey
  • HEPS falls sharply at RCL Foods
  • Another blow for SPAR as the chairman and deputy chair step down
  • Thungela banked excellent profit growth in H1

ASP Isotopes’ quarterly results show how early the company is on its journey (JSE: ISO)

The numbers need to look very different in the next few quarters

ASP Isotopes is firmly in storytelling mode. The company needs to be, as they need investors to keep believing in the technology being built.

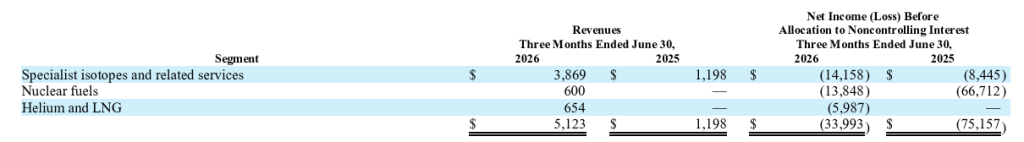
The release of quarterly results provides this table as an elegant summary of the substantial gap between revenue and losses:

Yes, that’s a net loss for the quarter of $34 million vs. revenue of $5 million.

Now, these are early days in the group’s commercial journey. The segments aren’t operating anywhere near their full potential. As a sign of just how much still needs to happen here, one customer represented 10% of the company’s consolidated revenue over six months!

If ASP Isotopes achieves what it has promised investors, then the future will look very different. Investors don’t have to wait long to see whether management can deliver on promises, as ASP Isotopes has set itself at least two major targets for the second half of 2026. They’ve promised initial commercial shipments of enriched isotopes. They’ve also assured investors that production of helium by Renergen is around the corner.

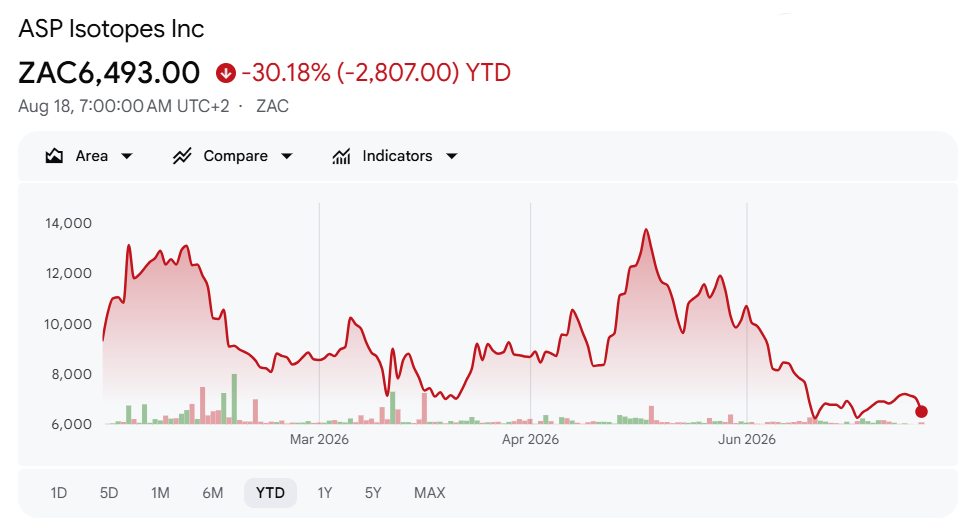
The market isn’t exactly forming an orderly queue to buy the stock in anticipation:

Either management is right, or the market is right. We will find out in the next few months.


HEPS falls sharply at RCL Foods (JSE: RCL)

The sugar and pet food segments have had a tough time

RCL Foods’ trading statement for the year ended June 2026 is a continuation of where the difficult interim period left off. It’s unfortunate that HEPS from total operations has dropped by between 30% and 35%.

There’s a nuance here around discontinued operations after the unbundling of the stake in Rainbow Chicken (JSE: RBO) and the disposal of Vector Logistics in the prior year. This adjustment is unlikely to materially change the picture.

It’s worth noting that HEPS from continuing operations (rather than total operations) for the six months to December 2025 was down by 30.6%, so the challenges have already been visible in the numbers.

The note on impairments gives us a clue about one of the pressure points. The Sunshine cash-generating unit was impaired due to difficulties in recovering volumes after the labour disruption at the Durban factory in December 2024. This is why earnings per share (rather than HEPS) is down by between 50% and 55%. Impairments aren’t cash losses, but they do indicate where value has been lost.

But the far bigger worry is the Sugar segment, which has been far from sweet due to deep sea imports assaulting the local industry. With tariffs proving to be ineffective, local industry market volumes fell by 10.3%.

This drove more local production into the lower-priced export market. Local industry exports may have been 48.3% higher, but international raw sugar prices were down by 22.6% – and that’s before we consider the effect of the stronger rand! The export market isn’t where RCL wants to play.

The current tariff is clearly not protecting local industry. But the counterargument is that food inflation must be kept as low as possible to assist marginalised South Africans. Do we prioritise local industry, or the cost of food for consumers?

These are complex matters with many factors that need to be weighed up by policymakers. You can be sure that a food producer is going to lobby for stronger tariffs to protect their business from imports. Government’s job is to find a balance. I will also say that the huge difference between local and international sugar prices means that serious questions need to be asked about the economic sustainability of our sugar industry in a global trade environment.

Moving on, the Pet Food segment was impacted by production issues related to food safety. Volumes fell by 20.5% as supply was constrained. There were also higher stock write-offs.

At least the Culinary and Baking segments provided “good performances” – but clearly not enough to offset these other issues.

Detailed results are due for release on 31 August.


Another blow for SPAR as the chairman and deputy chair step down (JSE: SPP)

I discussed this on the radio yesterday evening

Things are just going from bad to worse for SPAR. The shares have hit a new 52-week low in response to the news that Mike Bosman and Dr Shirley Zinn have resigned as chairman and deputy chair respectively.

The pressure of SPAR’s deteriorating relationship with its franchisees appears to have taken its toll. A lot of unpleasant things have been said publicly about SPAR’s management by franchisees, so I can believe that the behind-closed-doors activity must have felt threatening to these directors. The juice stopped being worth the squeeze for them.

Stephen Grootes invited me to discuss the broader SPAR issues with him on The Money Show on Monday evening. It was the lead segment, with roughly 8 minutes of insight into SPAR and the broader retail sector. Check it out below (it starts within the first minute of this podcast):


Thungela banked excellent profit growth in H1 (JSE: TGA)

But revenue wasn’t the main driver here

Thungela’s results for the six months to June 2026 cover a period in which coal prices finally turned the corner.

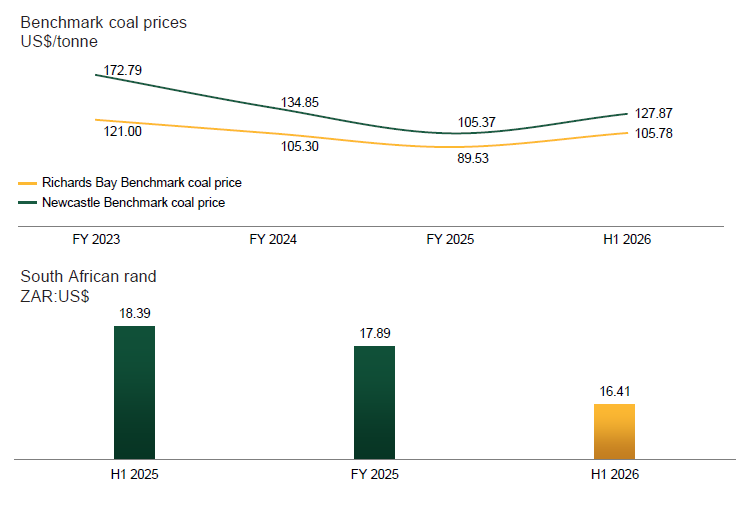
Energy security was a feature of this period due to the conflict in the Middle East, with benchmark coal prices responding accordingly. Some of this benefit was blunted by the rand’s appreciation against the US dollar, as shown beautifully in this excerpt from a slide in Thungela’s results presentation:

Although the rand negated much of the coal price move, Thungela did enjoy improved performance at Transnet Freight Rail as a boost for export volumes. Transnet’s annualised run rate has improved by 5.5%. I cannot stress enough how important it is to our resource-heavy economy that Transnet performs.

Despite the overall positivity, revenue only increased by 2%. Foreign exchange and domestic revenue pressure offset much of the benefit of strong export prices and volumes.

Things got a lot more exciting further down the income statement though, particularly with a much lower cost of production at Ensham in Australia due to higher volumes. This drove a 91% increase in group adjusted EBITDA and a 150% increase in HEPS.

Sustaining capital expenditure was flat for the year. Adjusted operating free cash flow jumped by 291%. This easily supported dividend per share growth of 175%.

Thungela is taking a cautious approach with guidance for the full year. Despite such a strong interim period, they’ve maintained their guidance across key metrics.

The market took a somewhat more bullish view, with the share price closing 10% higher on the day! It’s still only 11% up year-to-date though, having come off sharply from the peaks in March/April as conflict intensified in Iran.


Selected Nibbles:

  • Notable director dealings:
    • Two directors of Vunani (JSE: VUN) bought shares in off-market deals worth over R5.3 million in aggregate. This comes after recent buying activity by various executives. I’m not sure what’s going on at Vunani, but this level of buying is clearly bullish.
  • Unsurprisingly, Balwin (JSE: BWN) shareholders gave the Bidco offer a resounding approval. Holders of 98.48% of shares present at the meeting voted in favour of the scheme.
  • South Ocean Holdings (JSE: SOH) released a trading statement for the year ended June. HEPS has jumped from a loss of 9.31 cents to earnings of 8.02 cents.